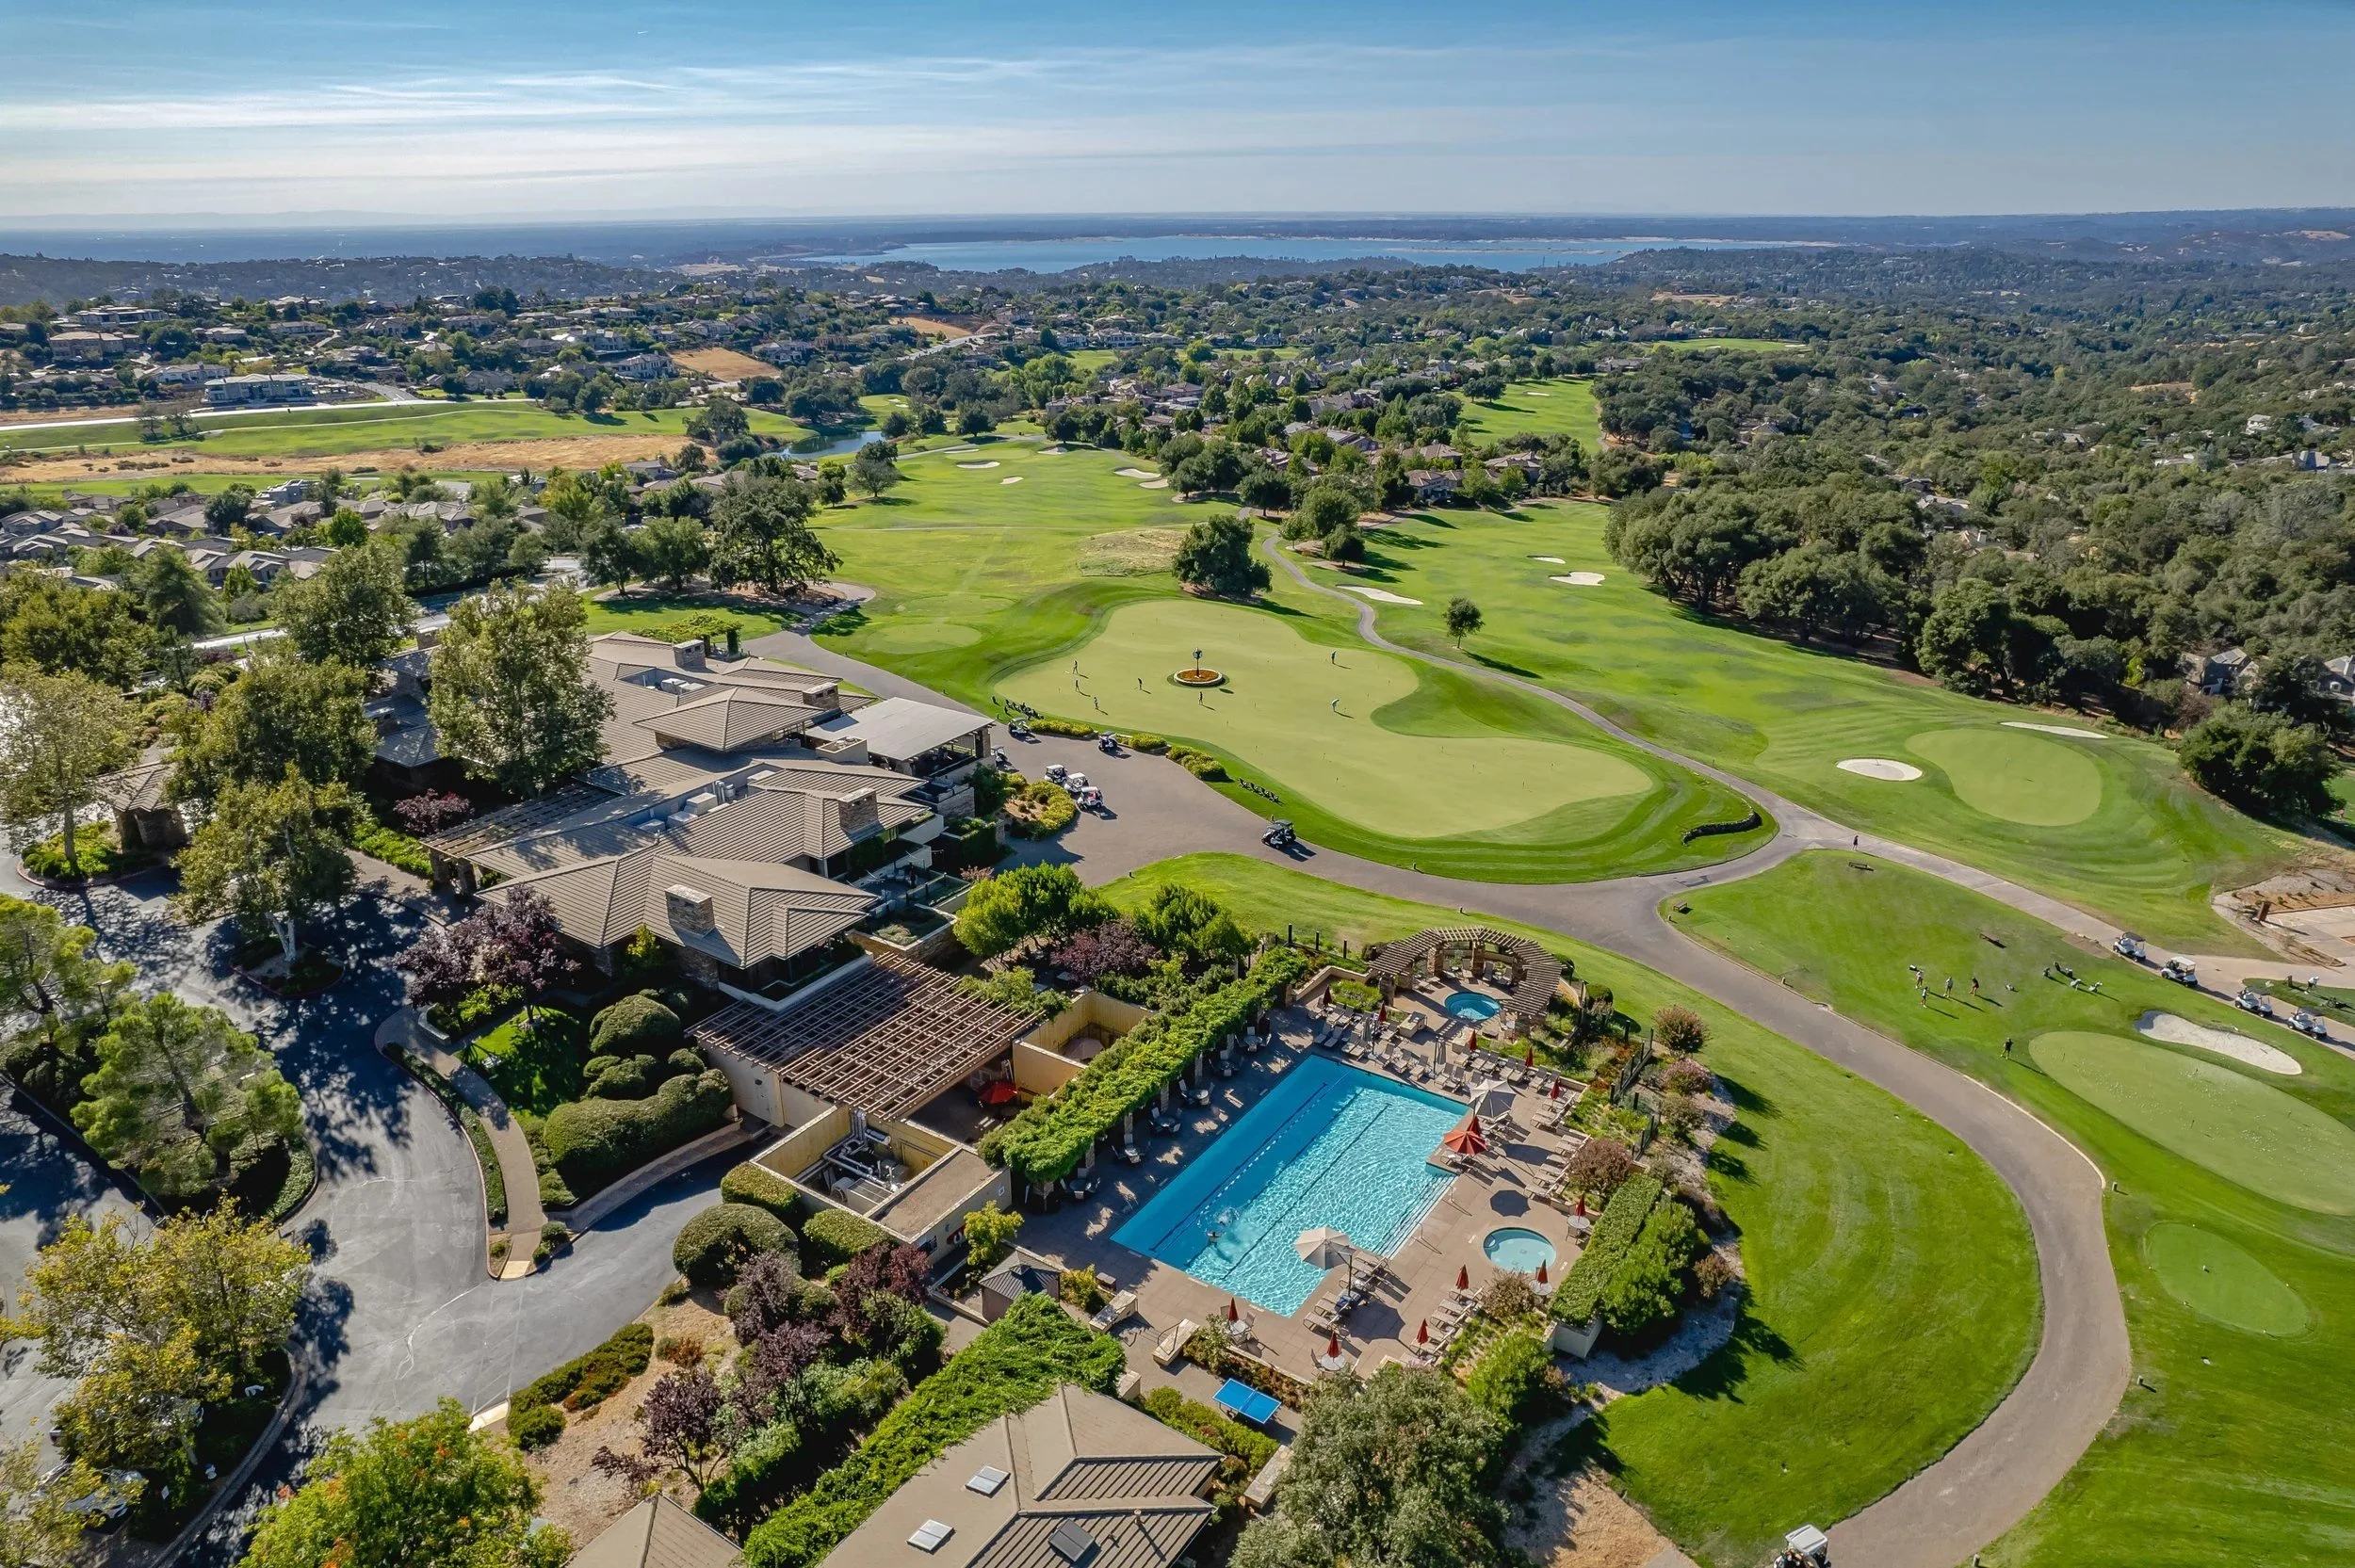
El Dorado Hills · Short Sale Guidance
Considering a short sale in El Dorado Hills?
Private, unhurried guidance from a local agent who specialized in short sales during the late-2000s downturn.
Confidential · No obligation · Nothing is listed until you decide
The first question
Is a short sale right for you?
A short sale is a sale for less than you owe, completed only with your lender's written approval. It may be worth exploring when one or more of these is true.
The lender, not the agent, decides whether to approve a short sale. If a sale isn't the right next step for you, I'll tell you plainly.
You owe more than it's worth
A sale today may not cover the loan balance and the costs of selling.
Payments have become hard
A job change, illness, divorce, or another hardship has changed the numbers.
You've had a lender notice
You want to understand a sale as one alternative to foreclosure.
You're open to selling
You would rather explore an orderly sale than wait and see.
Your options
Short sale vs. foreclosure, and other paths
A general comparison of how each path works in California. It is not legal, tax, or credit advice.
| Option | What it means | Lender approval | Timing, in general | Who to talk to |
|---|---|---|---|---|
| Short sale | You sell for less than you owe, and each lender agrees in writing to release its lien. | Required from every lienholder. Never guaranteed. | Marketing plus lender review, often weeks to several months. | A listing agent, plus an attorney or CPA for legal and tax questions. |
| Foreclosure | The lender enforces the loan, usually through a trustee's sale. | Not seller-driven. | Set by statute and the dates on your recorded notices. | A California real estate attorney or a HUD-approved housing counselor. |
| Deed in lieu | You transfer the home to the lender voluntarily, if it agrees. | Required. The lender may decline. | Varies by lender. | Your servicer and an attorney. |
| Loan modification | Your servicer changes the terms of the loan. | Required. The servicer decides. | Varies widely. | Your servicer or a HUD-approved housing counselor. |
| Traditional sale | A sale that pays off the loans and costs in full. | No short sale approval needed. | Typical local market timing. | A listing agent, and a CPA for tax questions. |
Credit and tax effects differ for each path. Please speak with a CPA and a California real estate attorney before deciding.
The process
How a short sale works
A general picture of the real estate side. Every loan and lender is different.
A private conversation
Your goals, your loans, and whether a sale looks realistic. No documents needed.
Value and options
A clear look at likely market range and costs, so we can see which path the numbers support.
Representation, if you choose
If you decide to move ahead, we sign a listing agreement. Not before.
Marketing and an offer
Your home is presented with care and discretion, and we negotiate an offer to submit.
Lender review
I prepare and coordinate the short sale package. That usually includes a hardship letter, financial information the lender requests, the purchase contract, and an estimated settlement statement. Review can take weeks or months.
Closing, if approved
With written approval from each lender, the sale closes and title transfers.
Local knowledge
El Dorado Hills details that shape a short sale
None of these rules out a short sale. Each one needs to be identified early and planned for.
HOA dues & liens
Unpaid dues can become liens that must be resolved before closing.
Mello-Roos
Community facilities district taxes affect buyers, net proceeds, and how a lender reads the file.
Solar & PACE
Leased or financed solar and PACE assessments need a payoff or transfer plan.
Second loans & HELOCs
Each lienholder decides separately. Approval from the first lender does not bind the second.
More on HOA dues and liens
Many El Dorado Hills villages have a homeowners association. Unpaid dues and related charges can become liens that have to be addressed before a sale can close, and the association's records control what is owed. In a short sale, the lender's approval and the settlement statement must account for those amounts. Recent HOA statements help, but you don't need them for a first conversation.
More on Mello-Roos and special taxes
Some homes sit in a Mello-Roos or community facilities district and carry a special tax on the property tax bill. The tax doesn't decide whether a short sale is approved, but it can affect the buyer pool, net proceeds, and how a lender reads the file. Your tax bill and title report show whether it applies.
More on solar leases, solar loans, and PACE
A leased or financed solar system may show up as a UCC filing or a contract, and a PACE assessment is collected on the property tax bill. A buyer and the short sale lender usually need a clear plan to pay off, assume, or transfer those obligations, which can add time. We can review the paperwork privately after we connect.
More on second loans and HELOCs
A second mortgage or HELOC is a separate lien, and that lender generally must consent in writing too. Approval by the first lender doesn't bind the second, and negotiating with a junior lienholder can add time. When you're ready, bring the servicer name and a recent statement for each loan.
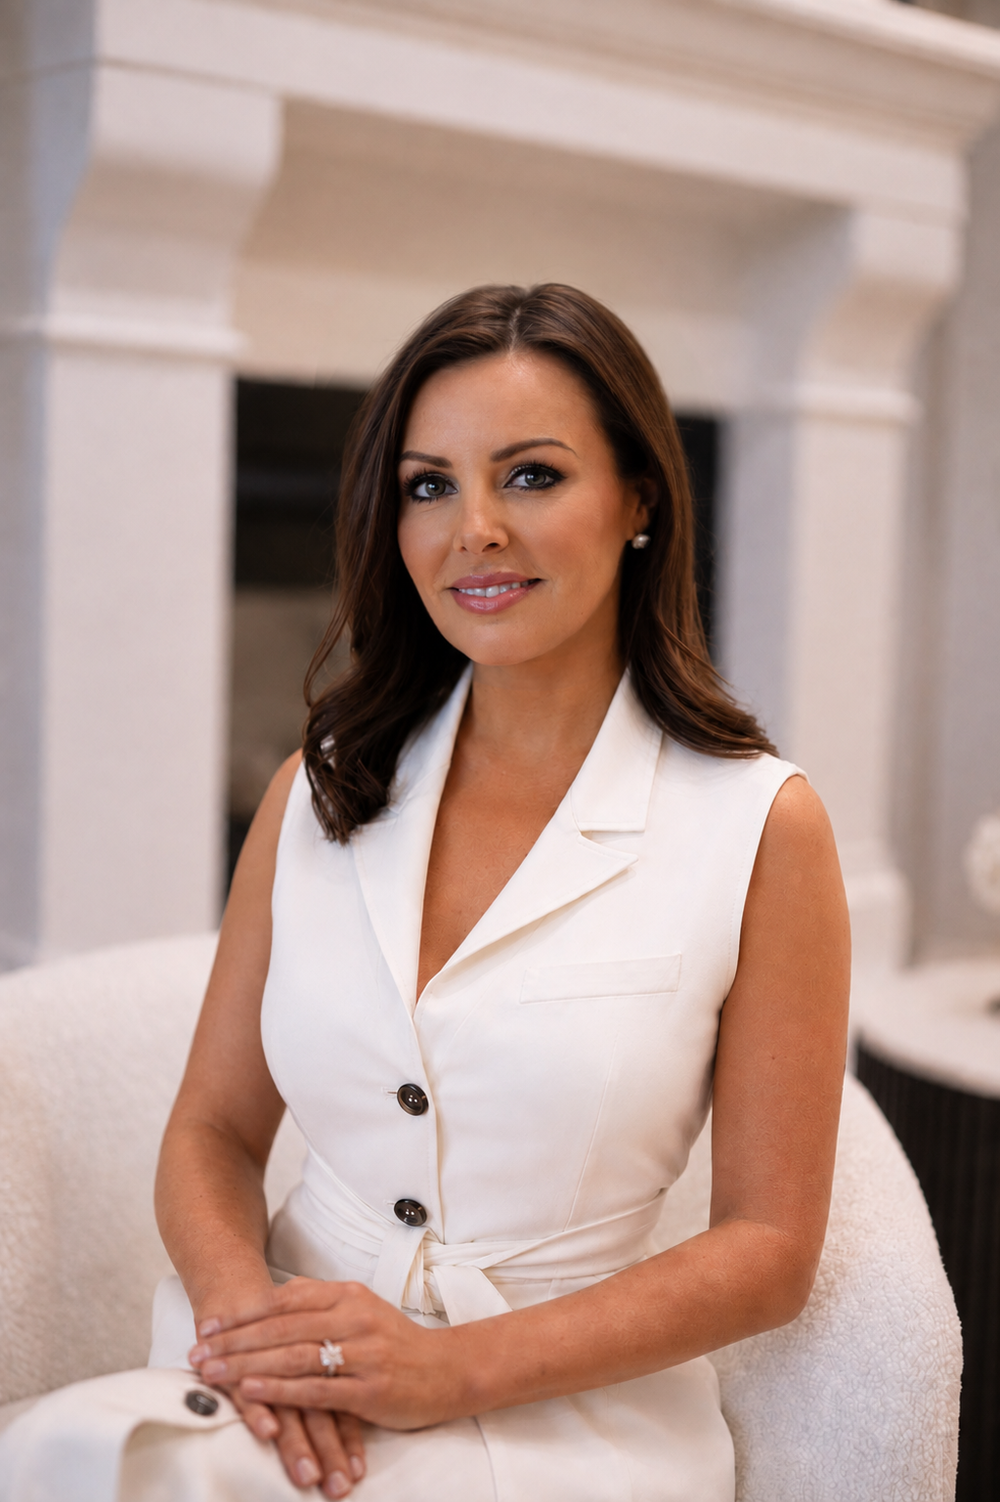
Why Stephani
Experience from the other side of the table
During the late-2000s downturn, I specialized in short sales, REOs, and loan modifications, working on the lender and negotiator side at Citi Home Solutions and on short sale and REO teams through 2012.
Today I represent sellers as their listing agent. That background helps me understand how lenders review a file. I no longer offer loan-modification services, and I do not offer foreclosure-consultant services.
I grew up in El Dorado Hills, and I serve homeowners in El Dorado Hills, Folsom, Cameron Park and surrounding areas.
I also help homeowners in Folsom, Cameron Park, and nearby communities work through short sales.
I can't promise a lender will say yes. I can promise a confidential conversation, honest guidance, and careful representation if we work together.
Stephani Menser Polley
REALTOR® · DRE #01898563 · Coldwell Banker Realty
About StephaniWhen you're ready
What's helpful to have on hand
Nothing is needed for a first conversation. Later, lenders commonly ask for:
- Recent mortgage statements for each loan
- Any notice from your lender or trustee
- A brief description of your hardship
- Recent pay records, tax returns, and bank statements
- HOA, Mello-Roos, solar, or PACE documents, if they apply
- A private phone number or email, if you prefer
Please don't send Social Security or account numbers until we've agreed on a secure way to share them.
Questions
What homeowners ask
Short, general answers. For your situation, please speak with a California real estate attorney or CPA.
Will I still owe money after a short sale?
It depends on your loan, the lender's written approval, and the law. California's anti-deficiency rules, including Code of Civil Procedure § 580e, can protect some sellers after an approved short sale of a one-to-four-unit home, but they have conditions and exceptions. Please confirm with a California real estate attorney.
Will I owe taxes, and how is my credit affected?
Possibly. Forgiven mortgage debt can be taxable, and you may receive a Form 1099-C. The federal exclusion for forgiven principal-residence debt covered debt forgiven before January 1, 2026, and other exclusions may apply. A short sale can also affect credit. Please ask a CPA, and see IRS Topic 431.
How long does a short sale take?
There is no standard timeline. Marketing, negotiating an offer, and lender review can each take weeks, and some files take several months, especially with a second loan, an HOA, or solar. I can't promise a closing date.
I've received a notice of default. Is it too late?
Not necessarily. In general, California law requires at least three months after a Notice of Default is recorded before a Notice of Trustee's Sale may be given, followed by a set notice period before any sale. The dates on your recorded notices control. A short sale conversation does not stop or postpone a trustee's sale, so please also speak with an attorney.
Should I stop making my mortgage payments?
I won't advise you to stop. Missing payments can have serious credit, legal, and foreclosure consequences. That decision belongs with your servicer and, if you wish, a housing counselor or attorney.
What does it cost? Is there an upfront fee?
There is no upfront fee to talk with me or to list your home. In a typical approved short sale, agent compensation and closing costs are paid from the sale proceeds, only if the lender approves them. Exact terms are set in writing in a listing agreement we review together first. The lender has the final say on what is paid from the proceeds. I don't charge an advance fee to talk, to "save" a home, or to obtain a loan modification.
Will my situation stay private?
Yes. I never advertise a seller's hardship, and if you decide to list, we'll choose marketing that feels comfortable. The form on this page is for a first inquiry only. Please also read the Privacy Policy.
Can you help me get a loan modification?
No. Loan modifications were part of my work in the late 2000s, but today I represent sellers as a listing agent. For a modification, start with your mortgage servicer or a HUD-approved housing counselor.
A quiet first step
When you're ready, I'm here.
You don't need every document, or a decision. Just a conversation.
Request a confidential conversation
Share how to reach you, and I’ll follow up privately. Please don’t include Social Security numbers, account numbers, or tax documents.
Office: 4370 Town Center Blvd, Suite 270, El Dorado Hills, CA 95762
Sources
Official information
Last reviewed November 2026
- California Code of Civil Procedure § 580e
- IRS Topic 431, Canceled debt
- CA Dept. of Real Estate, A Homeowner's Guide to Foreclosure
- HUD-approved housing counselor finder
- California Courts, Guide to foreclosures
Stephani Menser Polley is a licensed California real estate salesperson, DRE #01898563, with The Menser Real Estate Group at Coldwell Banker Realty, 4370 Town Center Blvd, Suite 270, El Dorado Hills, CA 95762. She is not an attorney, tax advisor, credit counselor, or lender, and nothing on this page is legal, tax, credit, or financial advice.
A short sale requires written approval from each lender or lienholder that must consent. Approval is not guaranteed. A short sale, a submitted file, or a conversation with an agent does not stop, postpone, or cancel a foreclosure. Forgiven debt can have tax consequences, and a short sale can affect credit. Anti-deficiency rules have conditions and exceptions.
This page describes real estate listing services only. It does not offer loan-modification, forbearance, foreclosure-consultant, or credit-repair services, and no advance fee is charged. Short sale, REO, and loan-modification work in the late 2000s is described as past experience. If you are already working with another agent, please let me know.
Equal Housing Opportunity