THE MENSER REAL ESTATE GROUP BLOG

Gloomy Economy Ahead
Top economists' outlook on the global economy for 2023 is "gloomy," with expectations of weak growth and a likely recession, according to a World Economic Forum report published on the opening day of Davos.
The World Economic Forum summarized the thoughts of some top economists in its January 2023 Chief Economists Outlook, released to coincide with the group's annual meeting in Davos, Switzerland, which kicked off on Monday.
"Although there are some grounds for optimism, such as easing inflationary pressures, many aspects of the outlook remain gloomy," the report said, citing "continuing economic uncertainty and policy challenges of historic proportions."
Close to two-thirds of the 22 chief economists surveyed by the WEF said they thought that a global recession was likely in 2023, with 18% of them considering it "extremely likely."
"Global growth prospects remain anemic, and global recession risk high," the report said.
But the respondents — who came from a pool of experts at finance and business giants like UBS, Google, Microsoft, and Bank of America — expect to see huge regional variations in economic growth over the next year.
All of the economists said that they expected weak or very weak growth in Europe and 91% said they expected it in the US, while this figure was less than half for the Middle East, North Africa, South Asia, China, and East Asia and the Pacific. More than half of respondents said that they expected high inflation in Europe, compared to just 5% expecting to see it in China.
The WEF said that this likely reflected Europe's high energy prices, increases in interest rates, and "sluggish demand." In contrast, the gradual reversal of China's zero-COVID policies could boost the country's economy, though it may stint production if more people get infected with the virus.
Companies including Amazon, Goldman Sachs, and Salesforce have already announced layoffs this year, and the chief economists expect job cuts like these to continue. 86% percent of the survey respondents said they expect multinational businesses to cut operational expenses, with 78% expecting workers to be laid off. Most economists said they expected companies to pass higher costs onto customers, too.
But despite the largely pessimistic outlook, the report highlighted how some of the dominant concerns in the global economy currently could weaken over the course of the year.
Two-thirds of the respondents said they expected the cost-of-living crisis to become less severe by the end of 2023, while close to two-thirds said they were optimistic that the energy crisis will have begun to improve by the end of the year. JPMorgan CEO Jamie Dimon, however, forecast in December that Europe's energy crisis would worsen and likely last for years.

December 2022 - Luxury Market Report for Placer County
View the real estate market data for Placer County California luxury homes for December 2022.

December 2022 - Luxury Market Report for Sacramento County
View the real estate market data for Sacramento County California luxury homes for December 2022.

December 2022 - Luxury Market Report for Lake Tahoe, California
View the real estate market data for Lake Tahoe California luxury homes for December 2022.

124 Briggs Ranch Drive, Folsom, CA 95630
Quality built by Winncrest homes in 1991, this timeless residence boasts 1,925 square feet of single story living. As you enter into the grand foyer, you are greeted with tall ceilings in the formal living and dining room. Chef’s will delight in the gourmet kitchen with prep island and a dining nook. The family room features beautiful built-in cabinetry, wood flooring and a fireplace.
Down the hall, double doors lead to the office with a closet, a bedroom, full bathroom and the master suite. Amenities of the luxurious master suite include a walk-in closet, a linen closet, double vanities, shower stall, soaking tub and access to the backyard.
The private 10,890 square foot lot features a spacious covered patio, a dining deck, garden, a fruitful lemon tree, mature landscaping, a storage shed, and a seasonal stream. This striking home presents plenty of parking with an oversized three-car garage and possible boat parking along the side of the home. NO HOA OR MELLO ROOS!
Listed at $699,000
FHA 203k Loans: What Are They? What Are the Benefits?
FHA 203k loans are designed to help borrowers finance an older home that needs significant repairs.
To get an FHA 203k loan, you must work with an FHA-approved lender, which The Rojo Mortgage Team at UWL is approved!
You will also have to provide a detailed proposal of the work you want to do.
Getting a Mortgage Loan for a Fixer-Upper: A Primer on FHA 203k Loans
The idea of buying a fixer-upper and turning it into your dream abode can seem so perfect — every nook and cranny just to your specifications! The reality, however, can be harsh. When you realize how much it will cost to remodel, you often also realize that you can’t afford it. Or you find out that a lender won’t give you a loan because the home is considered “uninhabitable” as it is. That’s where an FHA 203k loan comes in.
An FHA 203k loan is a loan backed by the federal government and given to buyers who want to buy a damaged or older home and do repairs on it. Here’s how it works: Let’s say you want to buy a home that needs a brand-new bathroom and kitchen. An FHA 203k lender would then give you the money to buy (or refinance) the house plus the money to do the necessary renovations to the kitchen and bathroom.
Often the loan will also include: 1) an up to 20 percent “contingency reserve” so that you will have the funds to complete the remodel in the event it ends up costing more than the estimates suggested and/or 2) a provision that gives you up to about six months of mortgage payments so you can live elsewhere while you’re remodeling, but still pay the mortgage payments on the new home.
Which Repairs Qualify?
There are two main types of FHA 203k mortgage loans. The first is the regular or standard 203k, which is given for properties that need things like structural repairs, remodeling, a new garage, or landscaping; the second is the streamlined or limited 203k, which is given for energy conservation improvements, new roofing, new appliances, or non-structural repairs such as painting.
Among the other repairs that an FHA 203k will cover:
decks
patios
bathroom and kitchen remodels
flooring
plumbing
new siding
additions to the home such as a second story
heating and air conditioning systems
And more
The program will not cover so-called “luxury” improvements such as adding a tennis court or pool to the property. It also does not cover any improvement that does not become a permanent part of the property.
How Much Money Can You Get?
The maximum amount of money a lender will give you under an FHA 203k depends on the type of loan you get (regular vs. streamlined and purchase vs. refinance loan).
With a regular FHA 203k, the minimum amount you can borrow is $5,000.
With a regular FHA 203k loan, the maximum amount you can get on a purchase loan is the lesser of these two amounts:
The Nationwide FHA Mortgage Limits
OR
The appropriate Loan-to-Value (LTV) ratio from the Purchase Loan-to-Value Limits, multiplied by the lesser of:
110 percent of the After Improved Value (100 percent for condominiums), or
the Adjusted As-Is Value, plus the following:
Financeable Repair and Improvement Costs, for Standard 203(k) or Limited 203(k);
Financeable Mortgage Fees, for Standard 203(k) or Limited 203(k);
Financeable Contingency Reserves, for Standard 203(k) or Limited 203(k); and
Financeable Mortgage Payment Reserves, for Standard 203(k) only.
Refinance limits are similar but also take into account the amount of the existing debt and fees of the existing loan.
With a streamlined loan, you can get a loan for the purchase price of the home plus up to $35,000 with no minimum repair cost plus the cost for energy improvements. To determine the as-is value of the property or the estimated value of the property post-repair, you may need to have an appraisal done. You will be required to put down 3.5 percent, but the money can come from a family member, employer or charitable organization.
What Kinds of Properties Qualify?
Qualifying homes for a FHA 203k loan include:
A one- to four-family home that has been completed for a least a year
A home that has been torn down, provided that some of the existing foundation is still in place
A home that you want to move to a new location
The home cannot be a co-op, but some condos are eligible
Your property will also have to qualify under the usual FHA requirements. For example, its value cannot exceed a certain maximum amount, which depends on where you live.
What Are the Pros and Cons of These Loans?
The main benefit of these loans is that they give you the ability to buy a home in need of repairs that you might not otherwise have been able to afford to buy. Plus, the down payment requirements are minimal, and often you get decent interest rates (note that the interest rates and discount points will vary by 203k lender, so it’s important to make sure that you’re getting a good deal on the loan).
The downsides are that not all properties qualify, there are limits on the funding you can get and applying for the loan isn’t easy. For example, to apply for the loan you may need to hire an independent consultant to prepare the exhibits required (to get the loan, you have to provide a detailed proposal of the work you want to do and cost estimates for each item). Get more information on 203k loan by calling the Rojo Mortgage Team.

Welcome to our Blog!

- Categories -
- Recent Posts -
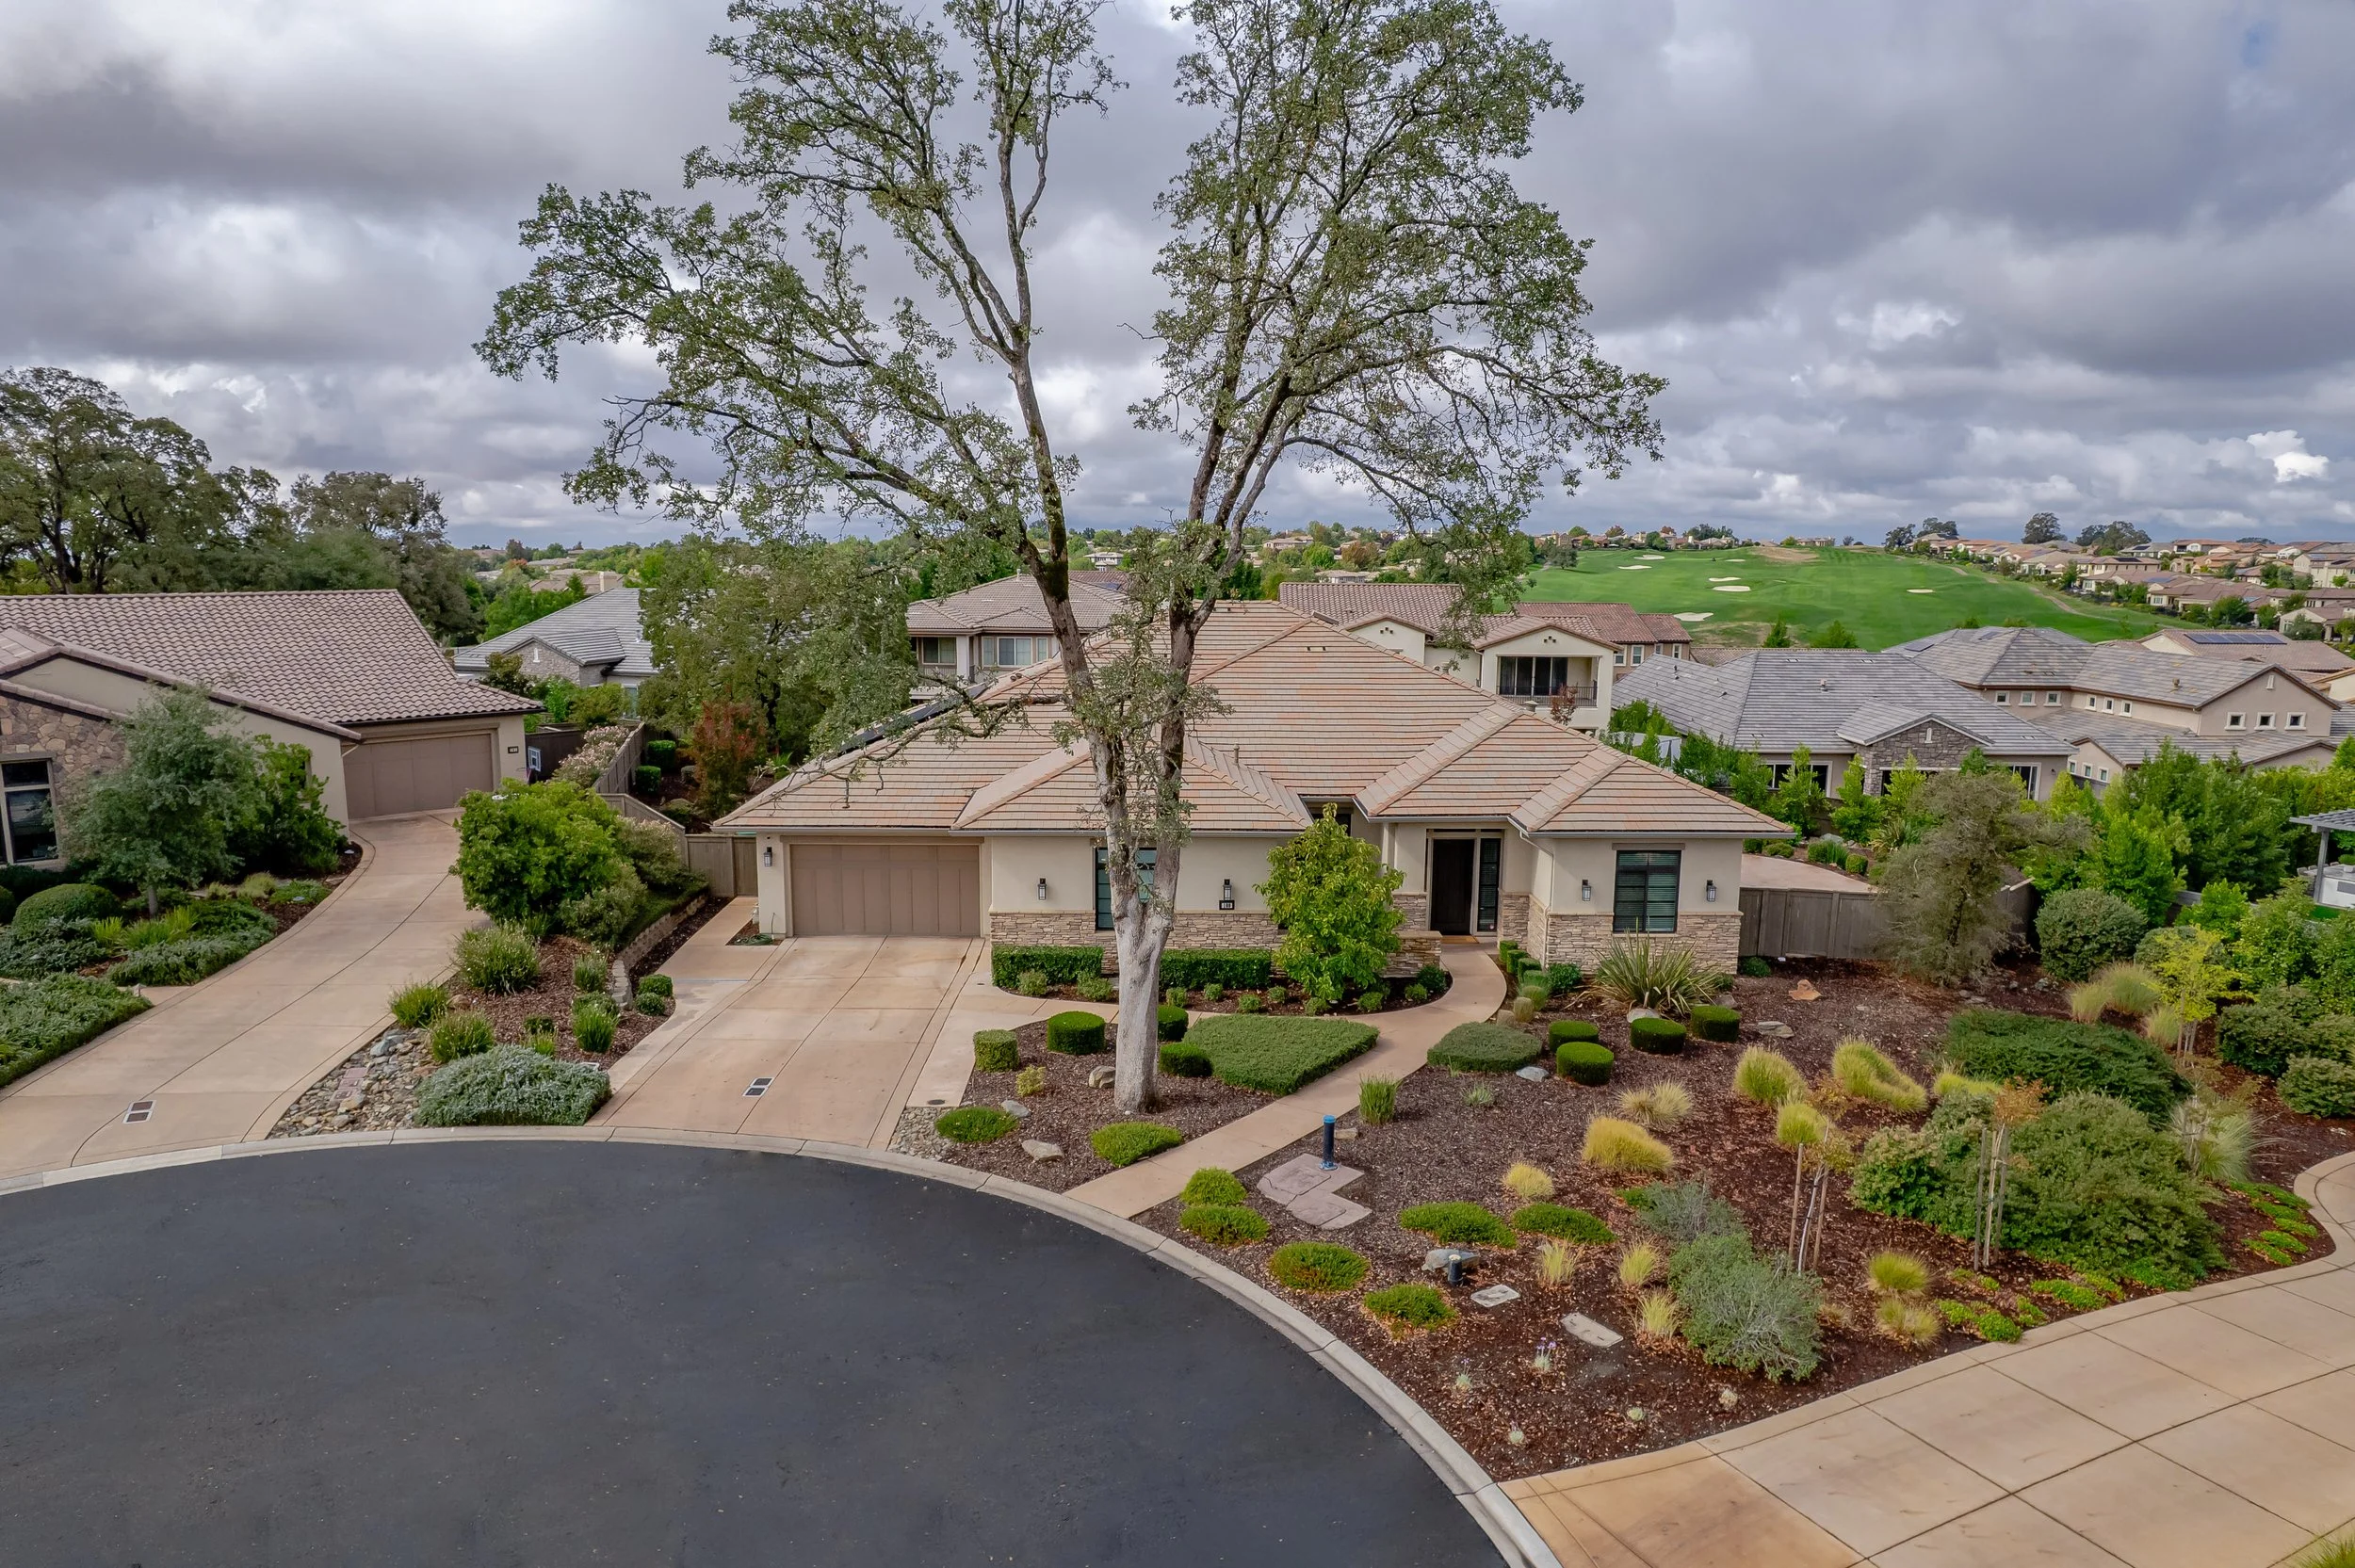

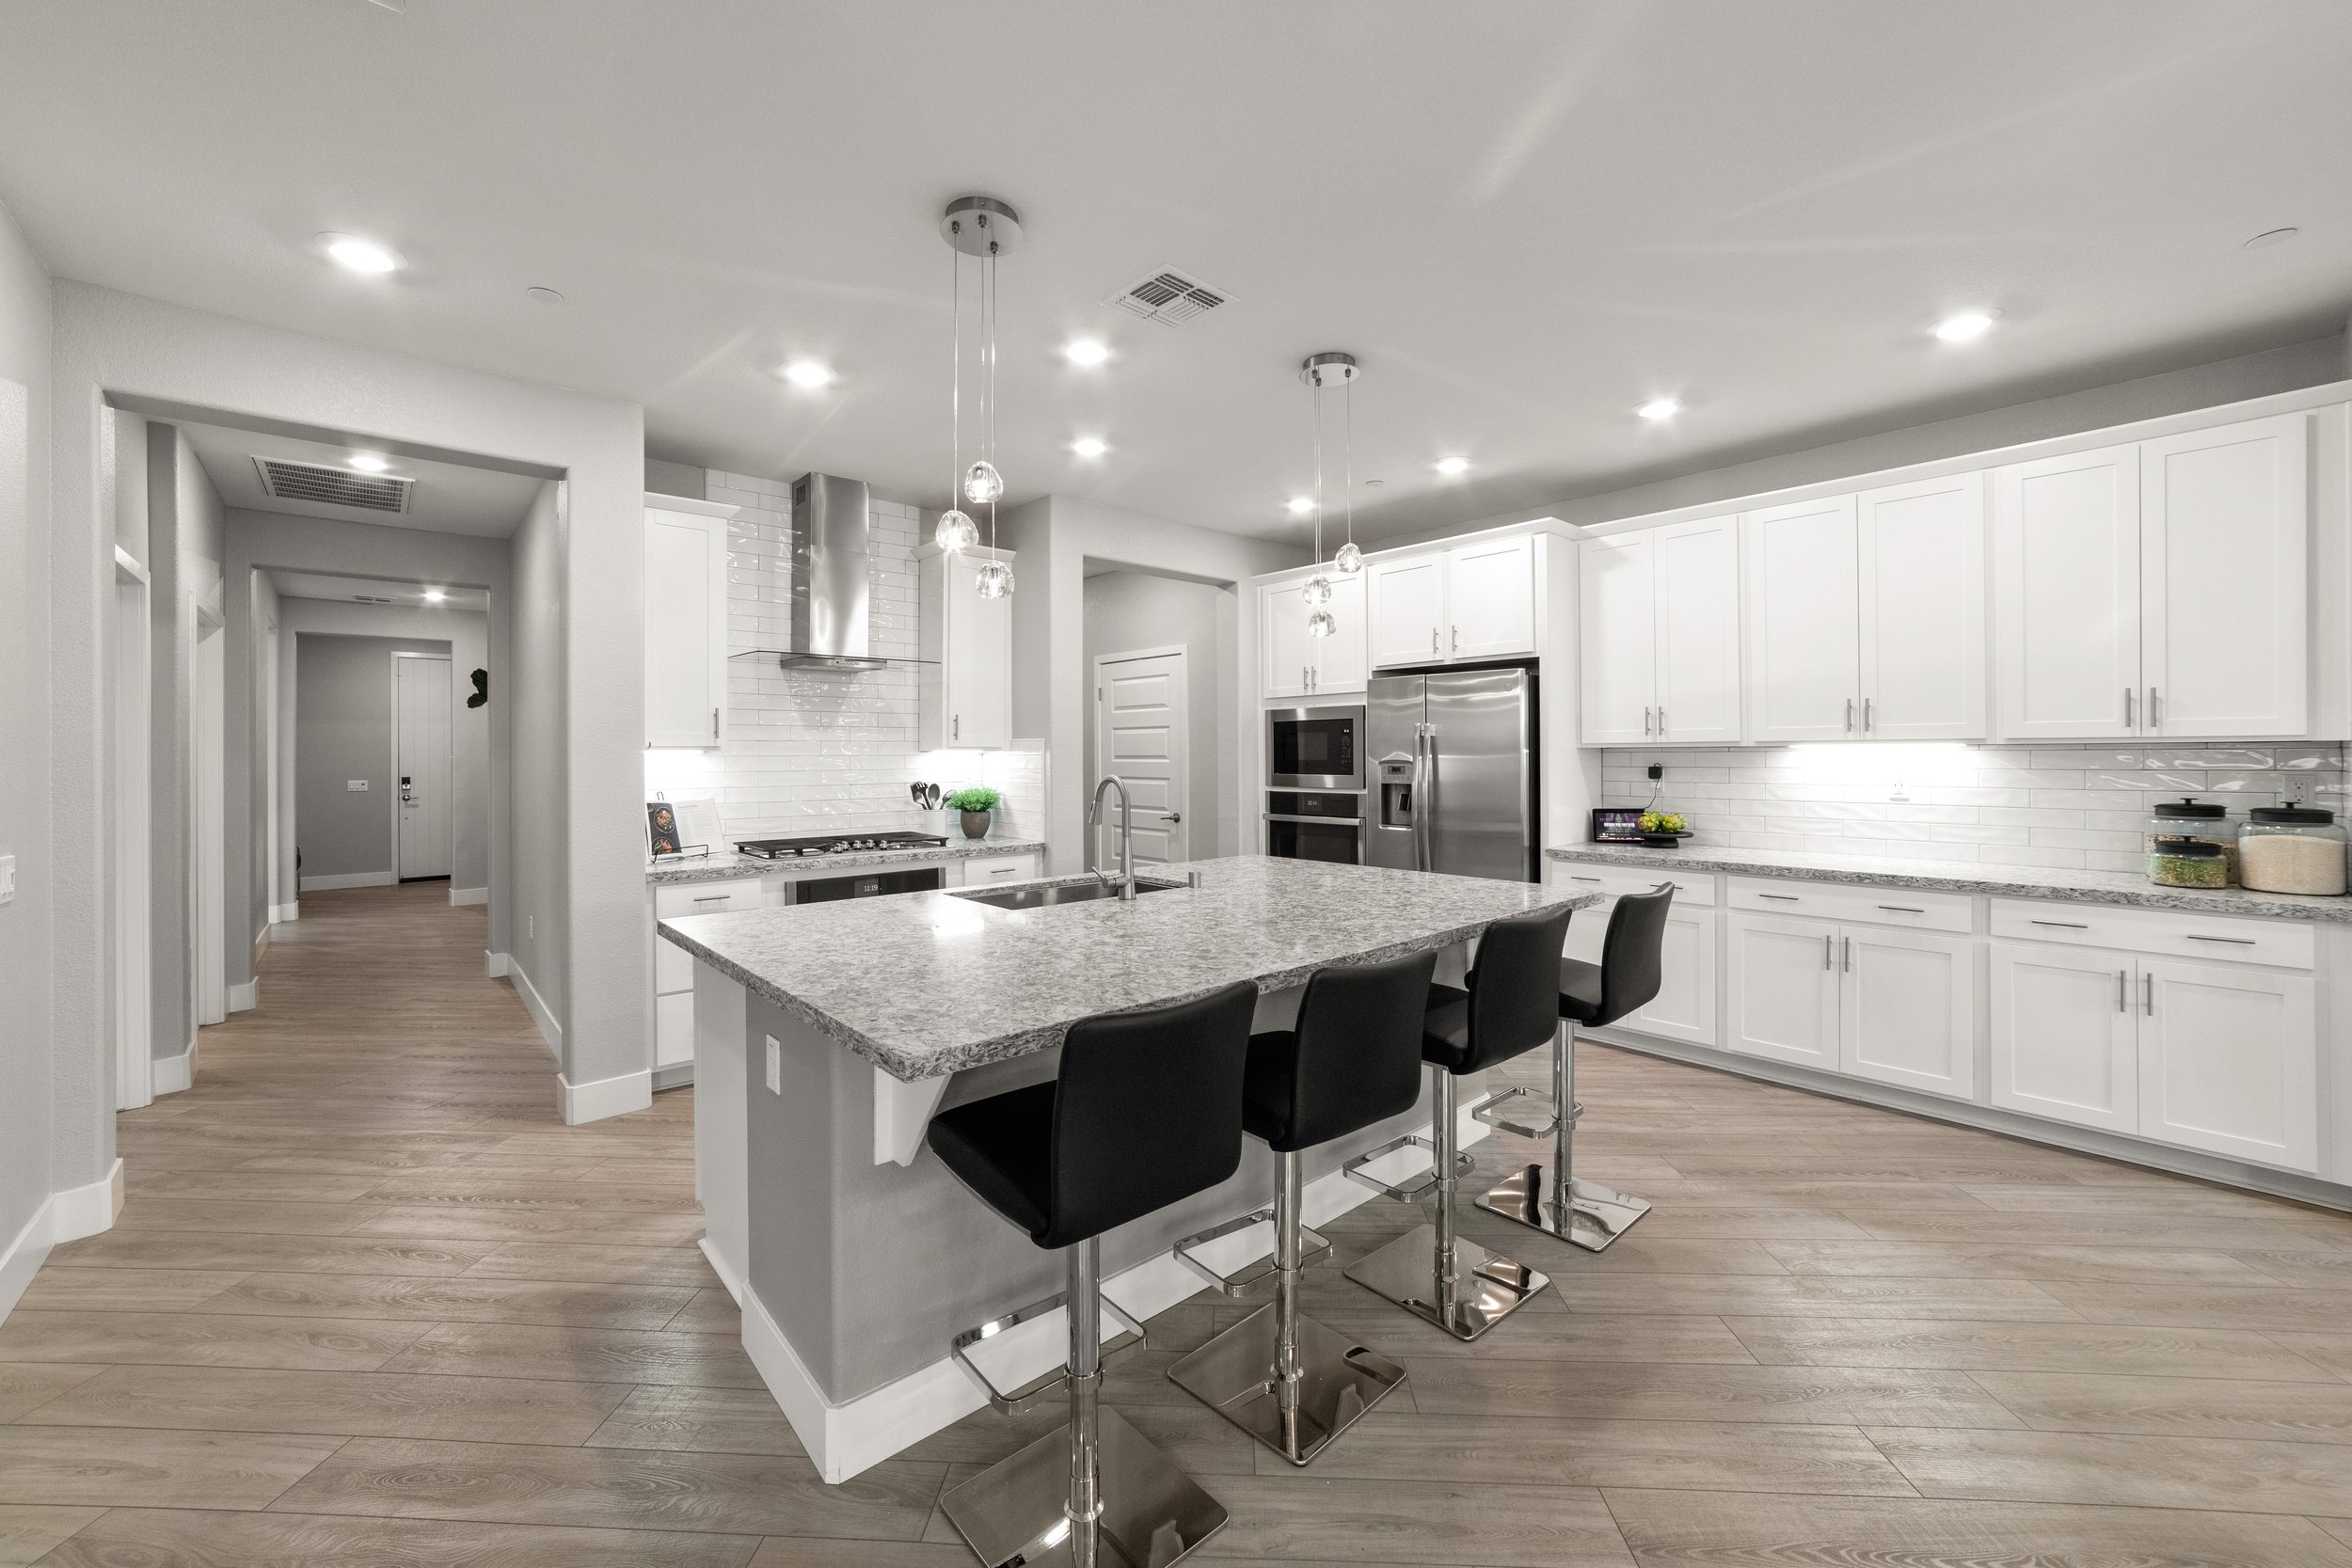
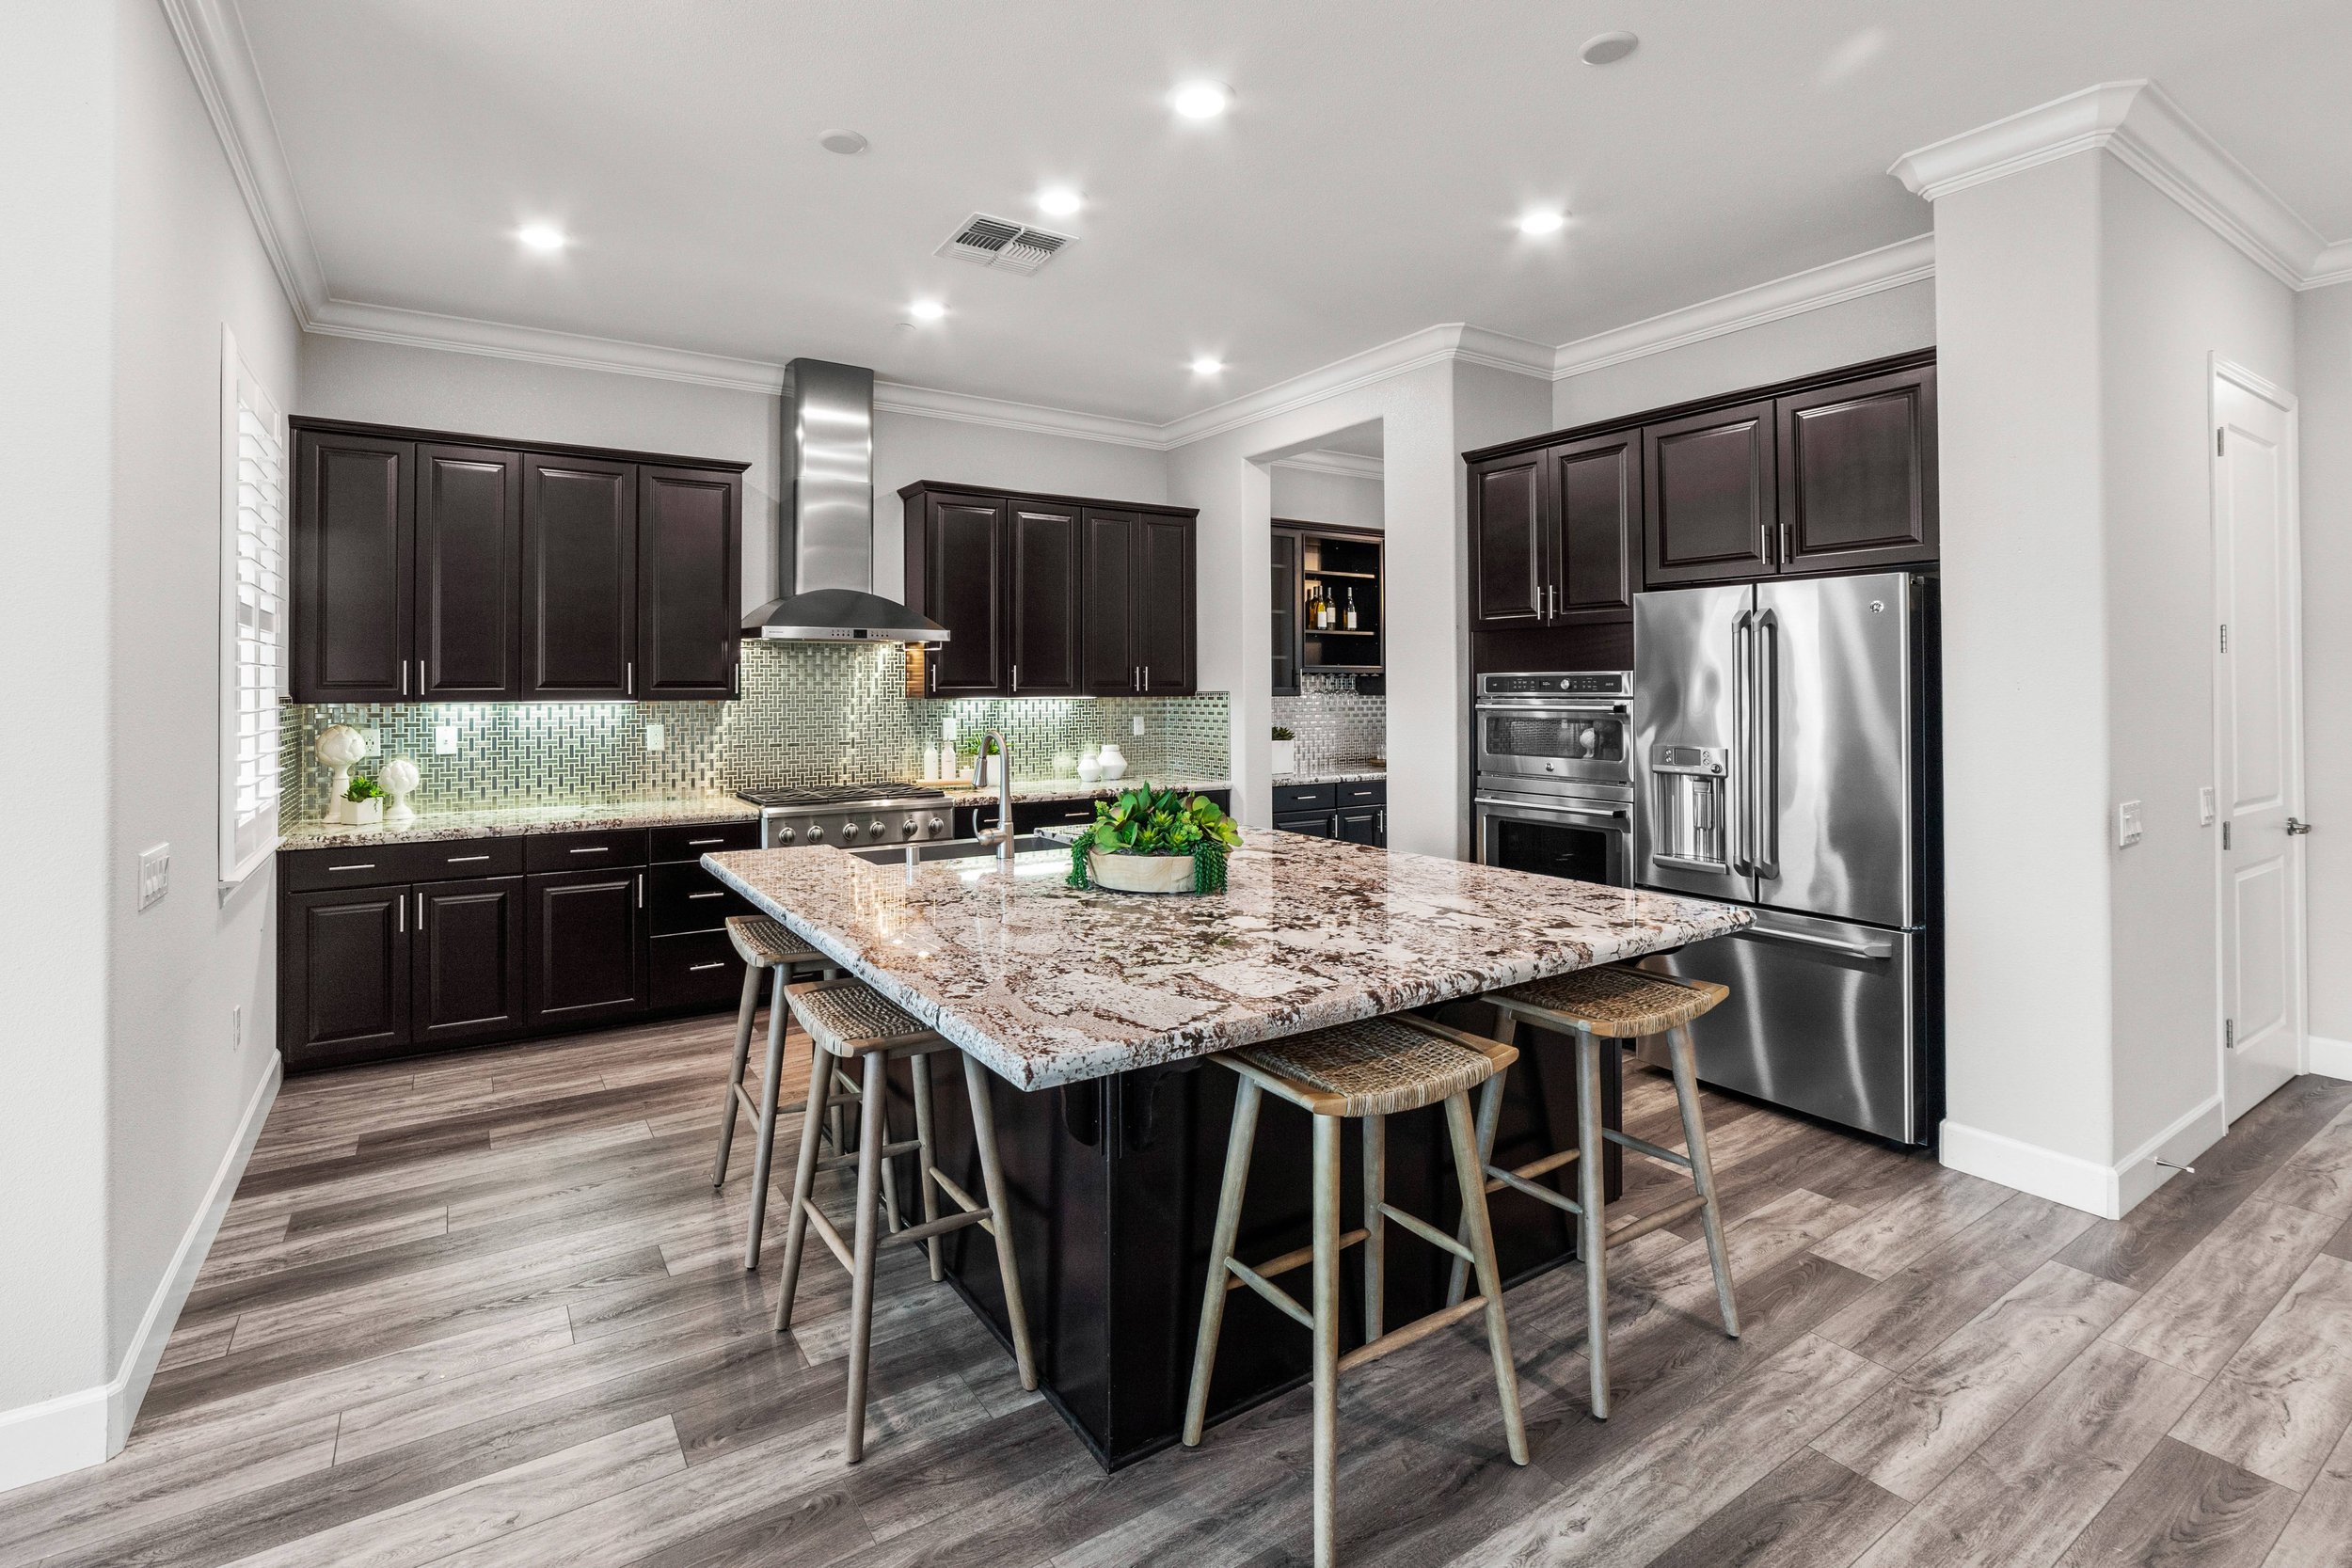

We helped our client purchase this Serrano home at a favorable price after it had been on the market for several months. When her relocation plans changed, she needed to sell without being here to manage the process.
The Menser Real Estate Group handled the preparation, staging, marketing, and negotiations, coordinating the details locally for our out-of-area client.
Our listing received two offers in just two days on the market. Approximately five months after her purchase, the home sold for $100,000 more than she had paid.
From purchase to resale, our team provided the local knowledge and hands-on support she needed as her plans changed.