THE MENSER REAL ESTATE GROUP BLOG
Understanding Why Mortgage Rates Are Higher
To understand why mortgage rates are higher first need to understand how to get mortgage rates and how they are determined.
First and foremost, mortgage rates have increased mostly because of runaway inflation. When inflation comes in year over year at 8.6%, the value of a fixed asset such as a treasury bond or mortgage-backed securities is severely eroded and so the demand for those investments decreases significantly. When that happens the price drops very quickly until there is a much better ROI for the investor. In the last few months, mortgage rates on a 30-Year Conventional Loan rose from around 3% to around 6%. A 3% increase in just a matter of 3 months.
Secondly, what has compounded the rate increase and also makes it difficult for a borrower to get a rate with no "points" aka upfront money, is the fact that there has been little to actually zero demand - no bids on the secondary market - for mortgage pools at certain rate coupons. Basically unheard of! But why is that?
Well, let's say you and I are an investor looking for a fixed asset and we like the return that an MBS pool (mortgage notes bundled together) can provide us. The rates are low so borrowers won't likely refinance for a long time, there is valuable servicing income to be earned because of this and the investment is backed by assets that are almost assuredly going to perform due to low loan to values, low rates, and strict underwriting guidelines. Okay great, let's do it!
Well...when rates increase as quickly as they have and we see a recession is imminent, it becomes evident that rates have gone higher than they will be in months or possibly a year. So how are we going to earn our investment back if the loans we invest in right now are almost all refinanced/paid off within a year? We won't! So we need to put a premium on our pricing and in addition to that servicers won't pay a premium for servicing rights on these new loans. This leaves mortgage pools with very little demand and very low to no premiums paid by the secondary markets. This compounds the increase in rate from just being market-driven to also adding in the fact that because rates went up so high so fast that some rate coupons have zero demand. In addition to this, the servicing premiums have decreased between 30 and 80%.
The result is that in order to have any profit on the mortgage rates offered, you will most likely have to pay a point(s) or fraction thereof in order to get a competitive rate.
Don’t let this dissuade you though. The Rojo Mortgage Team is still working harder than ever to secure the best rates for their clients. Visit our website at rojomortgage.com or call Scott Rojo at 916-548-3942 to see how we can help you.


May 2022 - Luxury Market Report for Lake Tahoe, California
View the real estate market data for Lake Tahoe California luxury homes for May 2022.
Good News for Homebuyers
The inventory shortage, high prices and rising interest rates have finally bitten.
Single-family home sales fell sharply by 16.6% in April to a seasonally adjusted annualized rate of 591,000, according to the latest Census Bureau data.
That was the slowest rate of sales since April 2020 during the earliest days of the COVID-19 pandemic, offering respite for buyers that the market is cooling.
What’s more, new home sales in March were revised downward significantly from 763,000 to 709,000, the Census Bureau said.
“The new home sales report released today by the Census Bureau clearly points to a housing market that has turned,” said Doug Duncan, chief economist at Fannie Mae.
Mortgage rates have risen 200 basis points since the end of 2021, putting pressure on existing home sales, mortgage applications, and homebuilder confidence, he said.
‘A sharper downturn in residential investment is now underway, and we will likely be revising downward our near-term home sales forecast.
Doug Duncan, chief economist at Fannie “However, today’s new home sales report is the sharpest indicator yet, with sales coming in well below both our own and consensus expectations,” Duncan said.
”The sales pace in April was similar in level to the slowdown that occurred the last time the Federal Reserve engaged in a tightening regimen in 2018,” he added.
”A sharper downturn in residential investment is now underway,” the Fannie Mae FNMA economist said, adding that he’ll revise downward his own sales projections.
A separate report released last Tuesday by Realtor.com suggested that people are prepared to buy and sell homes at ”more approachable price points.”
George Ratiu, senior economist and manager of economic research at Realtor.com, said the report “offers hope” for seller-buyers.
The Dow Jones Industrial Index DJIA, S&P 500 SPX and Nasdaq Composite COMP all closed higher on Friday, ending eight straight weeks of declines.
If you’ve been waiting for the prices to take a downturn, now is your time! With our lock and shop program you can lock in your interest rate while shopping for your home! Call me, I’d love to help you get your loan process started! Scott Rojo, United Wholesale Lending, 916-548-3942.

May 2022 - Luxury Market Report for Placer County
View the real estate market data for Placer County California luxury homes for May 2022.

May 2022 - Luxury Market Report for Sacramento County
View the real estate market data for Sacramento County California luxury homes for May 2022.

Big Reforms from Fannie Mae and Freddie Mac
Fannie Mae and Freddie Mac are implementing big reforms aimed at helping disadvantaged communities become homeowners and making sure homebuyers of color stay owners.
The initiative from the two federally backed home mortgage companies announced last Wednesday is the most sweeping overhaul since the housing crash in 2008. Some of the big-ticket items exclusively reviewed by USA TODAY include assistance with down payments, reserve funding for homeowners' emergencies and Fannie Mae and Freddie Mac are also rolling out a new credit reporting system that factors rent payments into creditworthiness scores, one of the biggest systemic barriers experts say keep renters of color from being able to purchase a The three-year strategy also laid out plans to increase fairness in the underwriting process, address appraisal disparities in multifamily housing, and finance permanent supportive housing programs primarily geared at providing housing for people experiencing homelessness.
Help is on the way
As part of the effort, Freddie Mac is expected to issue $3 billion in affordable housing bonds this year.
By 2024, Freddie Mac wants to fund the construction of 30,000 new multifamily units that allow credit-building for renters, accept housing choice vouchers and are designed inclusively for people with disabilities. They want to make the credit-building program available to 300,000 units.
The lender also wants to finance loan offerings in underinvested communities and neighborhoods at risk of losing affordability.
The announcement from Fannie Mae and Freddie Mac comes as median home prices and rents across the country skyrocket.
In the first quarter of this year, the median price of a home reached a record $428,000, according to the Federal Reserve Economic Data database, known as FRED.
Rent year-over-year increases have soared 90% across the nation, the most recent analysis by Rent.com found. In some markets, such as Austin and Oklahoma City, rents have shot up more than 112%, two years after a pandemic recession put nearly 40 million people at risk for eviction.
A majority of Americans also believe it's a bad time to buy a house for the first time since 1978.
According to a new poll by Gallup, only 30% of U.S. adults said it was a good time to purchase a home, driven by an annual inflation rate that accelerated to 8.5% in March and interest rates for 30-year fixed mortgages that climbed above 5%, up from 3% in 2020.
Taken together, everyday Americans are looking for relief in a priced-out housing market that has exacerbated inequities.
If you’re interested in more information, I’m here to help. Call Scott Rojo at 916-548-3942.
Welcome to our Blog!

- Categories -
- Recent Posts -
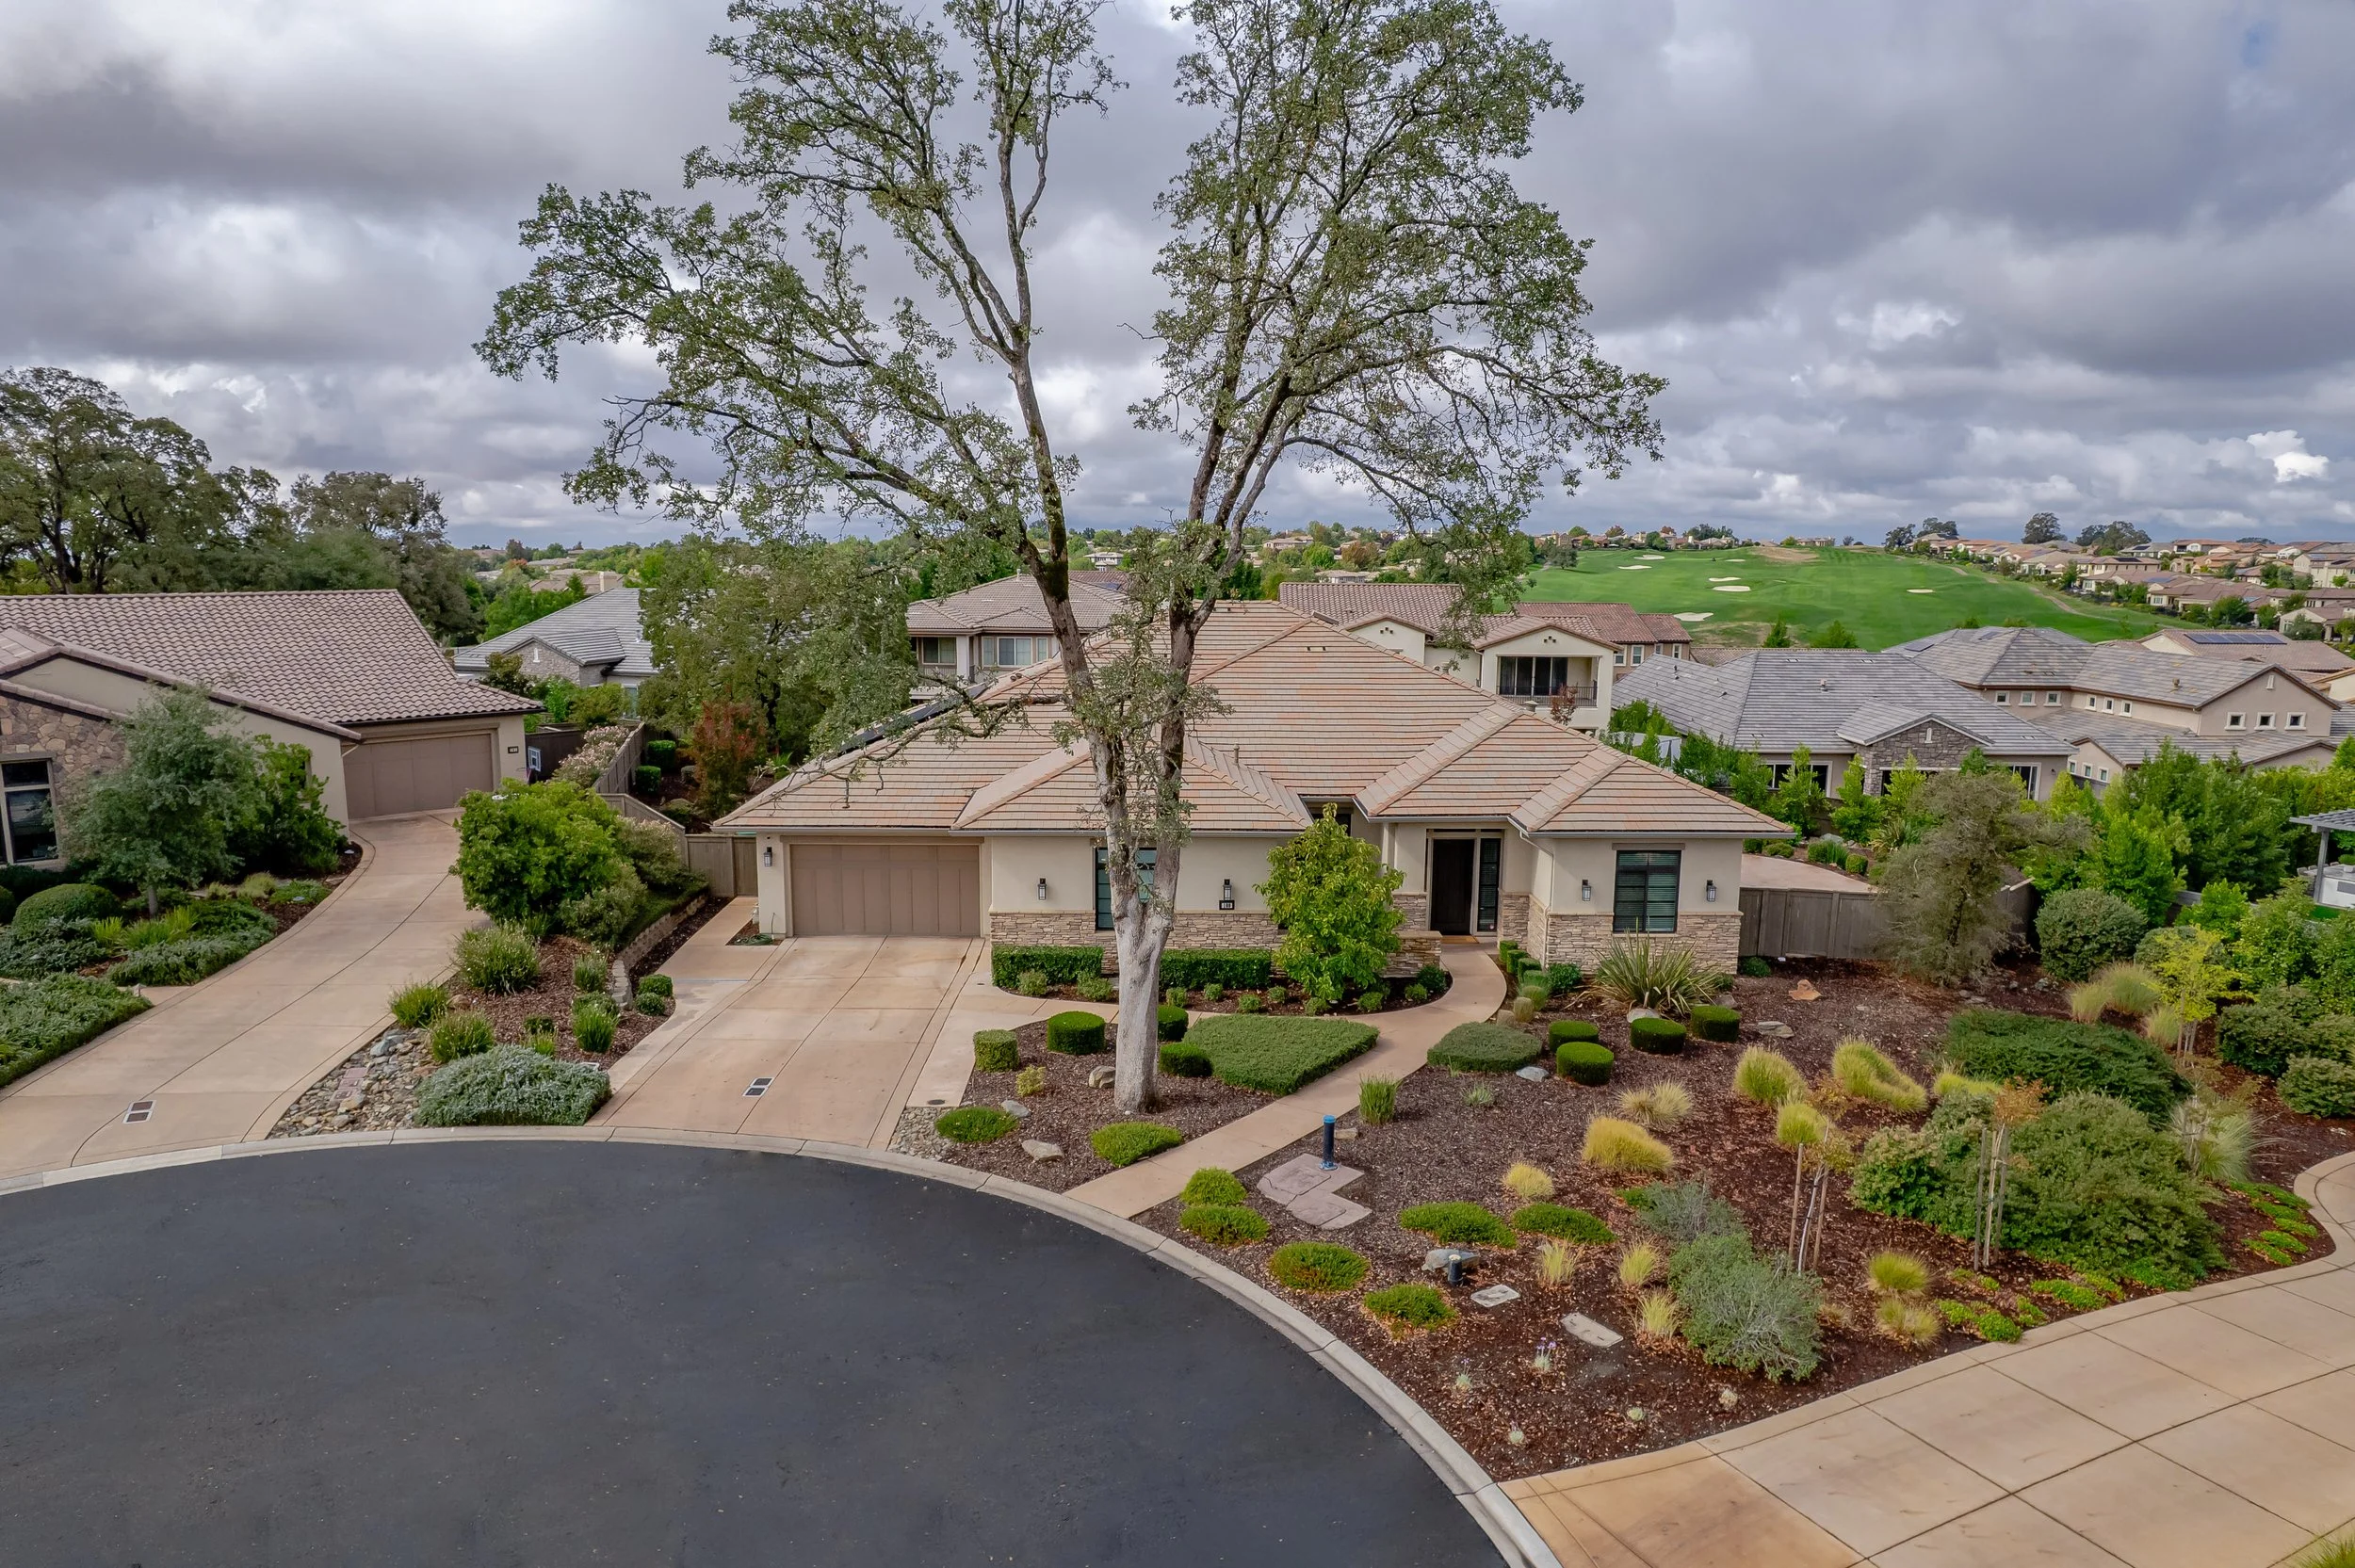

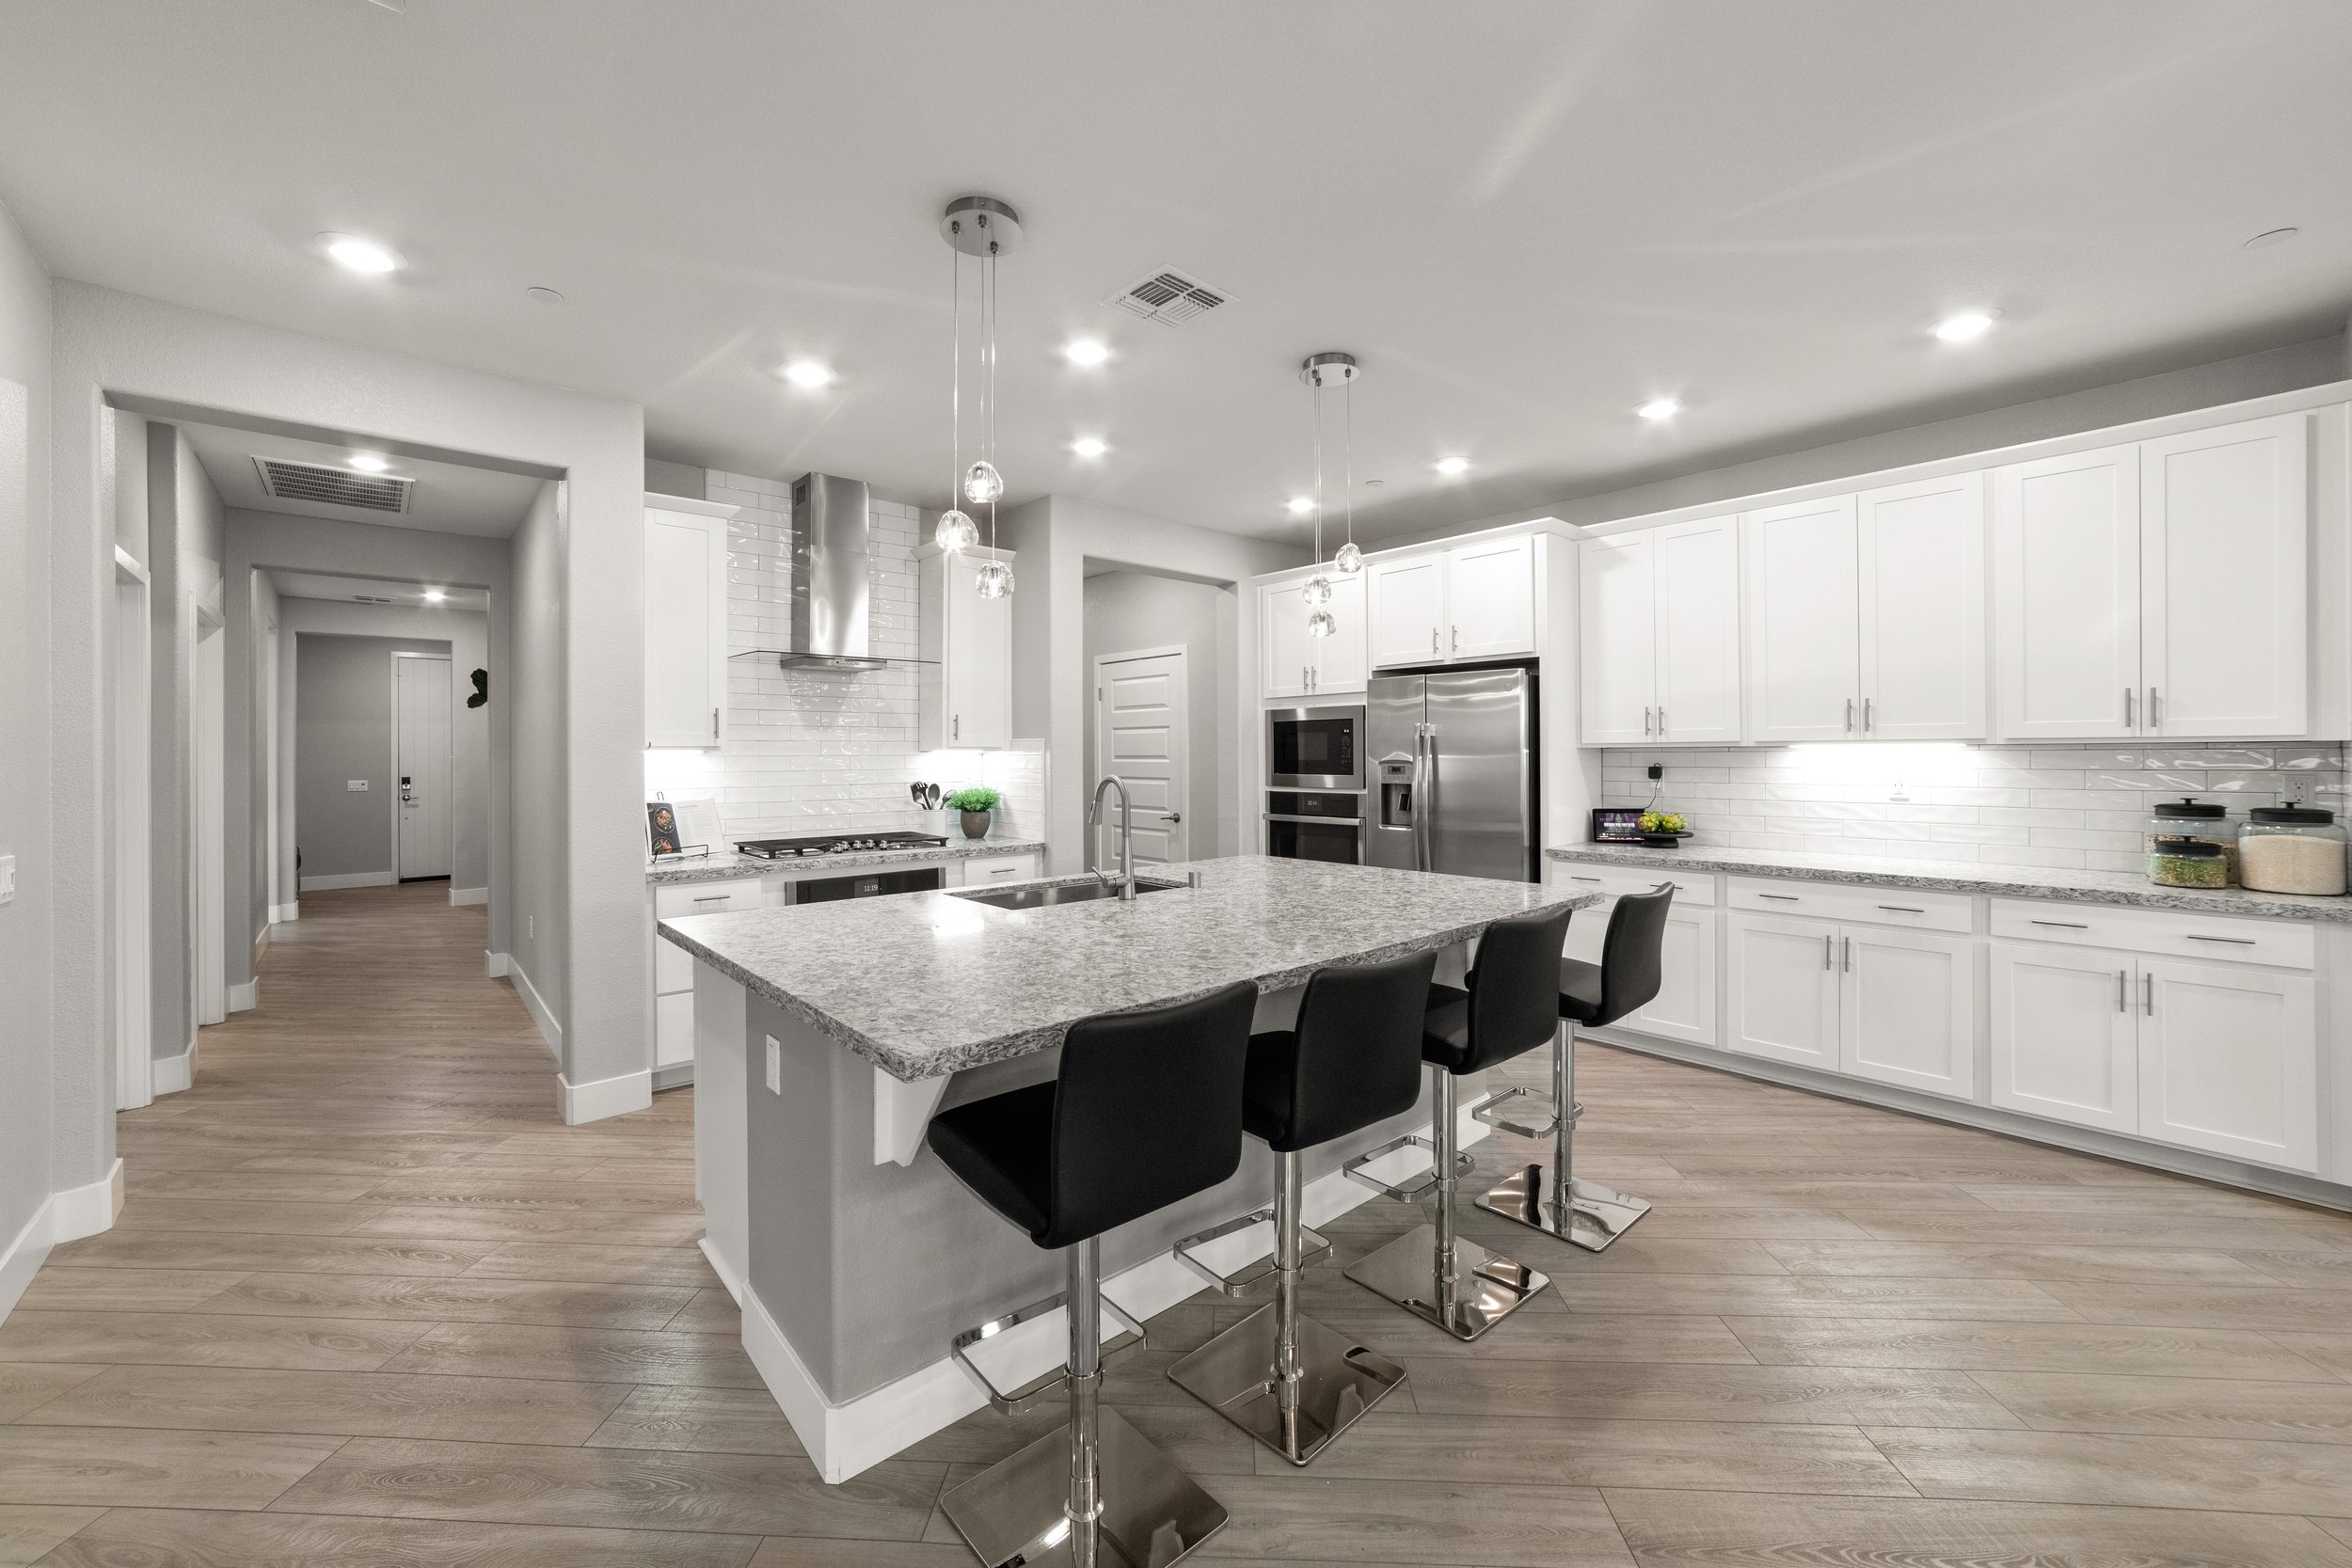
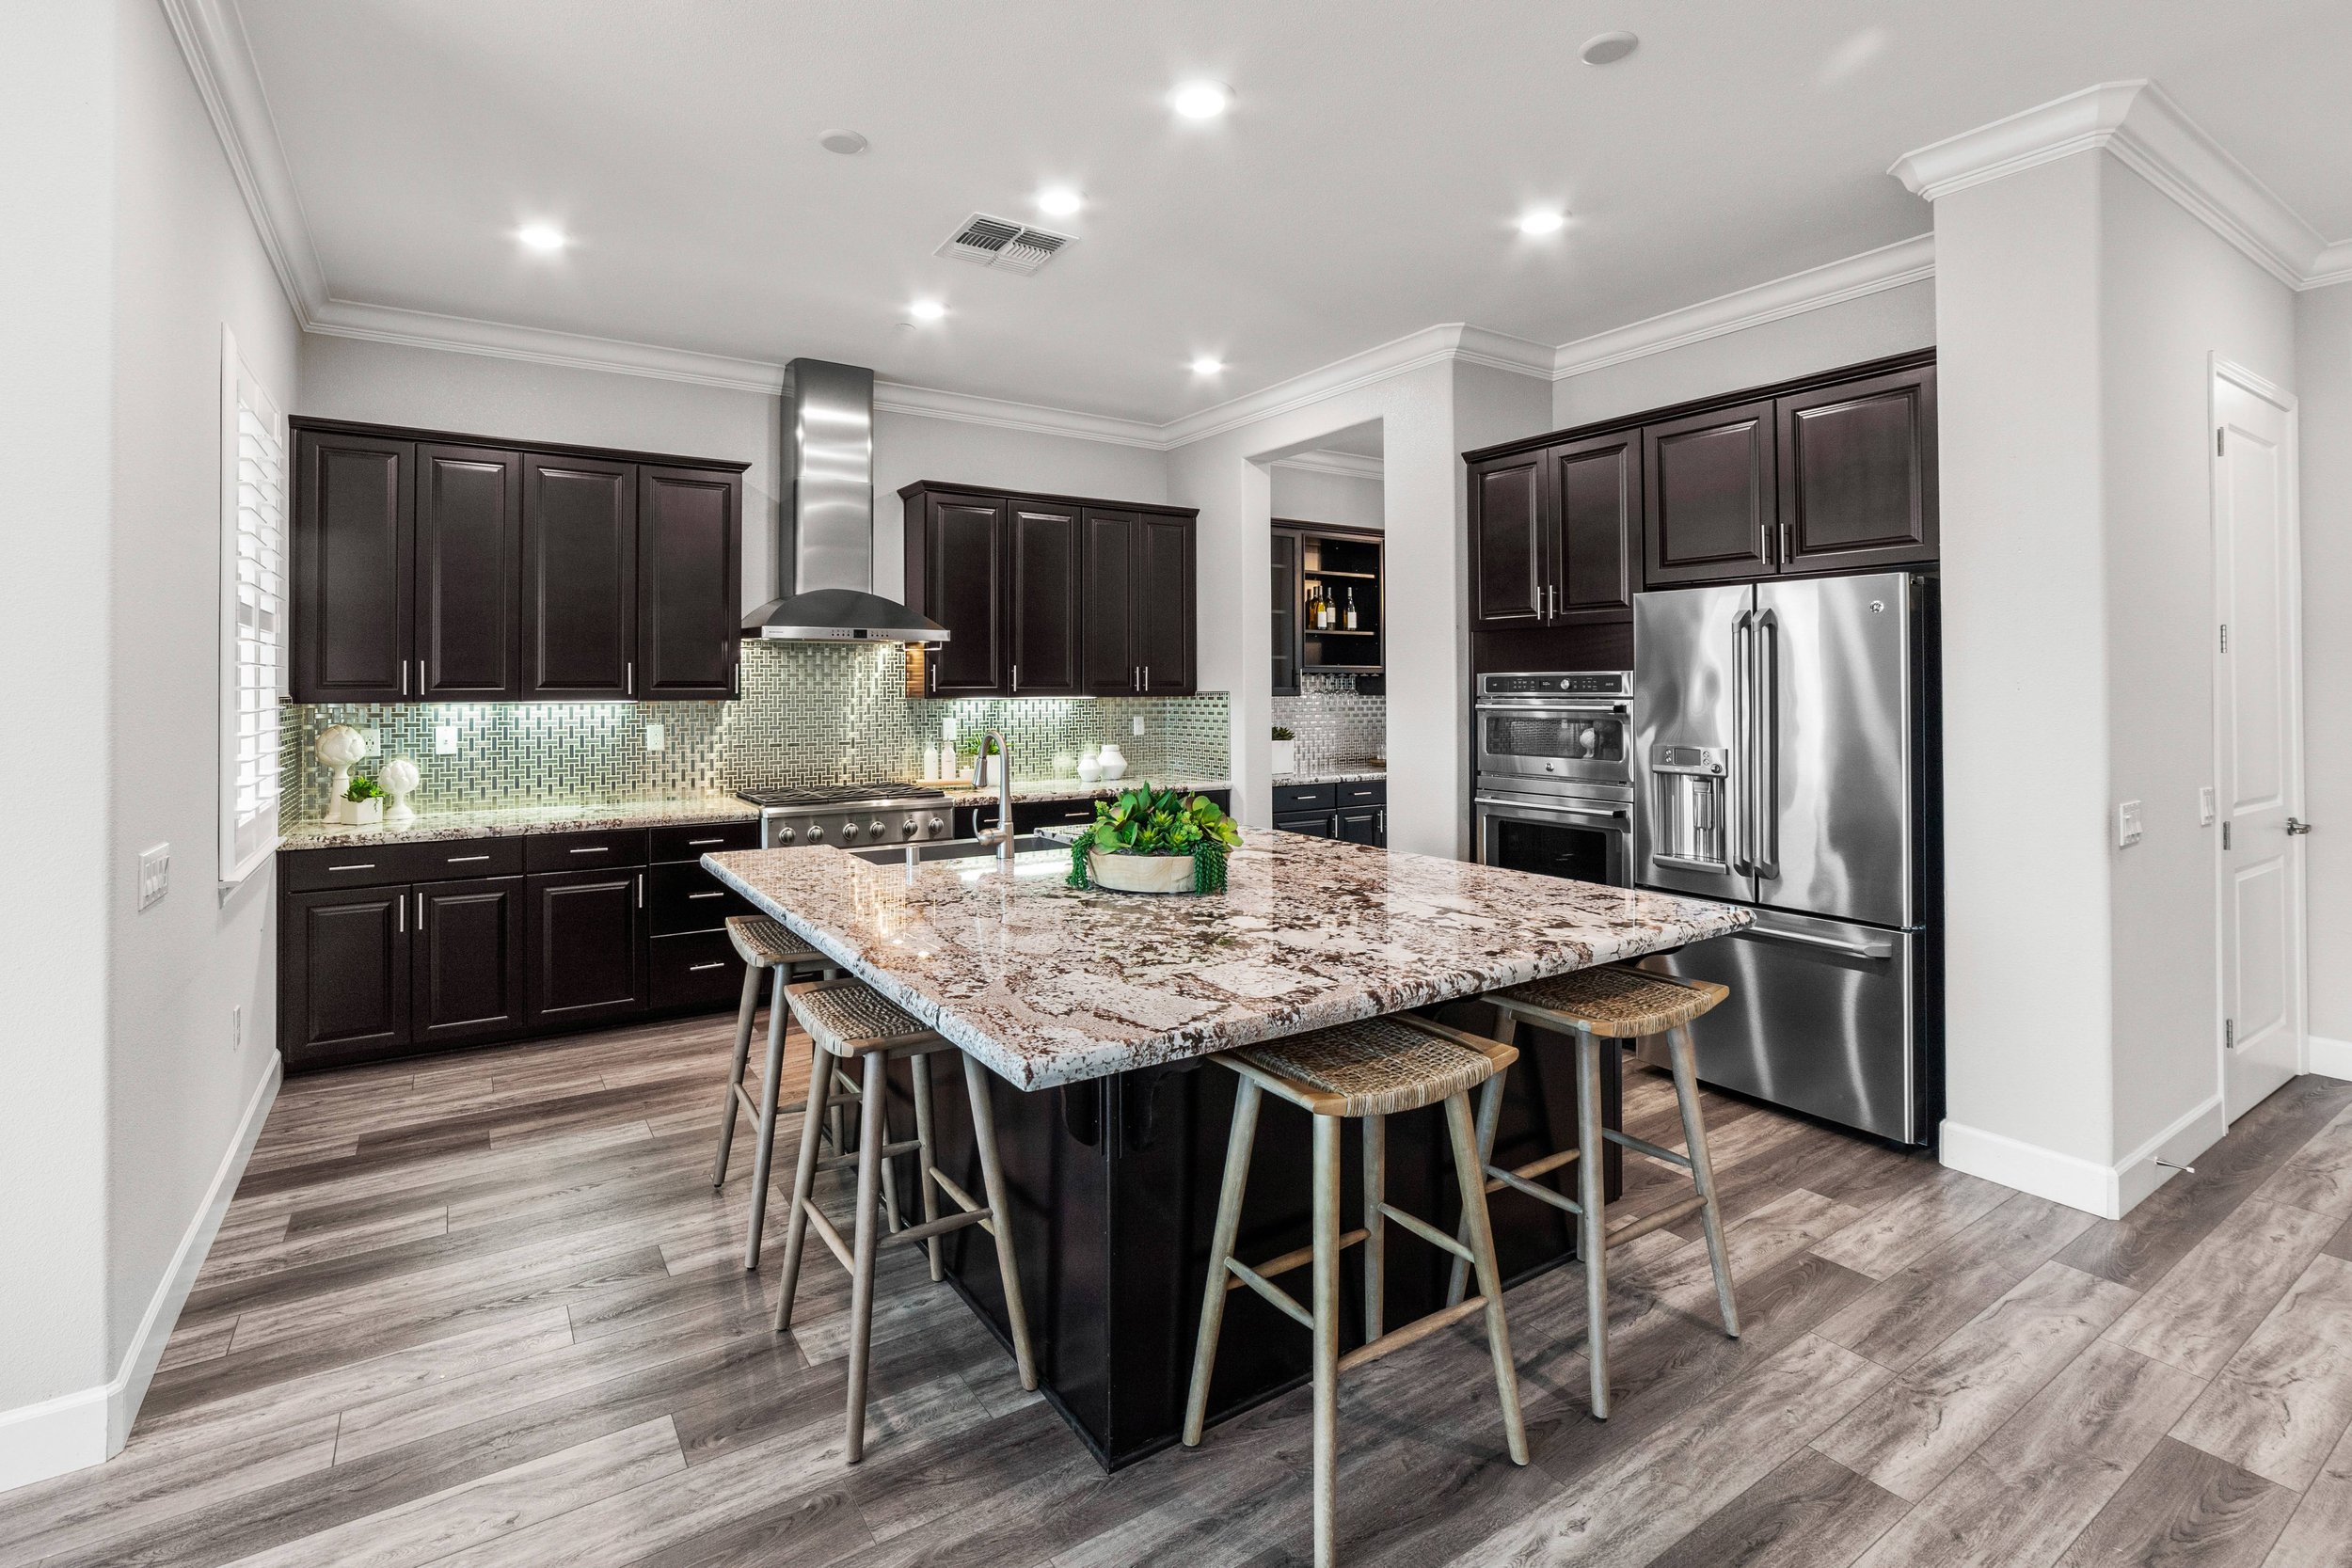

We helped our client purchase this Serrano home at a favorable price after it had been on the market for several months. When her relocation plans changed, she needed to sell without being here to manage the process.
The Menser Real Estate Group handled the preparation, staging, marketing, and negotiations, coordinating the details locally for our out-of-area client.
Our listing received two offers in just two days on the market. Approximately five months after her purchase, the home sold for $100,000 more than she had paid.
From purchase to resale, our team provided the local knowledge and hands-on support she needed as her plans changed.