THE MENSER REAL ESTATE GROUP BLOG
New Projections by the Federal Reserve
The Federal Reserve, after chasing inflation for the better part of a year, will look ahead as far as 2025 in new projections this week that will show more fully the depth and length of the economic “pain” its policymakers expect to be needed to stop the current surge in prices.
The tale so far is not a pretty one. The pace of price increases, which by the Fed’s preferred measure are running at more than three times its 2% target, have hardly budged in the face of the most rapid set of U.S. interest rate increases in about 30 years.
The projections, due to be published alongside the Fed’s latest policy statement at 2 p.m. EDT (1800 GMT) on Wednesday, will show just how aggressively U.S. central bank officials feel interest rates must rise to respond to the inflationary wave, and what economic cracks they see appearing as a result in terms of slower growth or higher unemployment.
Hopes for a “soft landing,” marked by a slowdown in inflation toward the 2% target without a recession, may not be gone: Policymakers are unlikely to project an outright downturn even as the outlooks compiled each September extend an additional year, in this case through 2025.
Outside the Fed, however, there is a growing sense that the path to a soft landing is unlikely. Some analysts estimate the unemployment rate, which hit 3.7% in August, may need to rise as high as 7.5%.
Traders in contracts tied to the Fed’s benchmark overnight interest rate now expect that rate to end the year between 4.25% and 4.50% - 2 percentage points higher than where it is now and a level last seen in late 2007.
“The probability of a softish landing falls materially” after U.S. inflation data for August showed just how persistent rising prices have become, Evercore ISI Vice Chairman Krishna Guha wrote last week. “Even assuming...it is still possible to bring inflation down...without a proper recession, the data and the response it will provoke substantially increases the risk that the Fed ends up overshooting badly and causing a recession anyway,” with the policy rate perhaps hitting as high as 5.00%.
AN END IN SIGHT?
The updated economic projections will give the clearest indication yet of Fed policymakers’ sense of the endpoint for rates, key information for investors trying to value assets or homebuyers wondering what a mortgage might cost next year.
Some officials have lately shied away from discussing the issue in detail, wary of setting expectations and then having to shift gears. The new projections, though, will include anonymous estimates from each official for where the policy rate should be at the end of 2022 and the following three years. The so-called “dot plot” of estimates from the seven members of the Fed’s Board of Governors and 12 regional bank presidents also includes outlooks for unemployment, inflation, and economic growth.
As long as inflation continues to move sideways rather than downwards, however, they face a dilemma over whether to raise interest rates to levels even higher than currently foreseen or hope the increases already flagged will eventually do the job.


August 2022 - Luxury Market Report for Sacramento County
View the real estate market data for Sacramento County California luxury homes for September 2022.
Is a Housing Market Crash Coming? Here's What Dave Ramsey Thinks
If you are thinking of buying a home, you may be hoping for a market crash. Home prices rose rapidly during the pandemic and mortgage interest rates have also been rising this year, so it may feel difficult to purchase a property under current conditions. But, if a crash happened and prices plummeted, houses would become more affordable. While some people believe a crash may be coming because they fear the real estate market became a bubble due to record low interest rates during COVID-19, this is not necessarily going to happen. In fact, if you listen to personal finance expert Dave Ramsey, no crash is likely to come at all for the foreseeable future. Here's why.
Dave Ramsey has a clear answer to the question of whether a housing market crash is imminent
Ramsey's opinion on whether a market crash is coming soon is unequivocal and very firm. "If you're in a position to buy or sell, don't wait on the 'Housing Market Crash' because it's not coming," the Ramsey Solutions blog reads.
Whether you're a buyer who is hoping for a crash or a seller who is fearing one, it's helpful to understand why Ramsey has such a definitive position on the direction of the real estate market. That's because he has a lot of data to back up his belief that prices are not going to fall anytime soon.
Here's why Ramsey doesn't believe a crash is coming
There are several key reasons why Ramsey thinks the housing market is not going to experience a major downturn anytime soon.
The first reason is that most projections suggest home prices are going to continue to rise over the coming year. While the increase won't be anywhere near the double-digit rise in prices that occurred in 2018 or 2019, it is expected costs will go up around 3% to 4% over the course of 2023. And this estimate makes sense because, as Ramsey points out, that "gets us back to the average increase for residential single-family homes the last 50 years."
Loans To Update Your Home
Ramsey also explained that supply and demand will drive the price of houses (and everything else). And demand is high while supply of homes is low. "Since we've had a shortage of homes for about the last two decades, plus the demand is high, the prices are therefore high." The supply dipped even more during the pandemic when no one wanted to sell a property and many people wanted to buy one as a result of record low mortgage rates.
But even post-pandemic, Ramsey does not believe that supply is likely to meet the demand anytime soon. There have been few new homes built in recent years, a lumber shortage cut construction rates further, and millennials have entered their prime home-buying years. "That's 12 million more households wanting to own a home today," Ramsey said. "This makes for too many buyers chasing too few houses."
Since all these points are valid ones, there's reason to suspect Ramsey is right about whether a crash is imminent, although no one can predict that with certainty. For that reason, those who are hoping to buy a home soon may not want to put off the purchase in hopes of a crash because that could backfire if high demand and continued low supply push prices even higher.
Rojo Mortgage Team at UWL
Mortgage rates are at their highest level in years—and expected to keep rising. It is more important than ever to use us so that we will secure the best rate possible while minimizing fees. Even a small difference in your rate could shave hundreds off your monthly payment.
You can get pre-approved in as little as three minutes, with no hard credit check, and lock your rate at any time. Another plus? We don’t charge origination or lender fees (which can be as high as 2% of the loan amount for some lenders).

5067 Garlenda Drive, El Dorado Hills, CA 95762
This spectacular residence is located in the prestigious gated community of Serrano, near one of the most beautiful hiking trails and around the corner from Bella Terra Park. Built by JTS, this 2,713 square foot home showcases a main level guest bedroom, full bathroom, an updated kitchen, a new HVAC, and stylish light fixtures. As you enter through the covered front porch, you are welcomed by vaulted ceilings in the living room and a beautiful view of the backyard. Chefs will delight in the stunning kitchen that overlooks the dining nook and family room with a fireplace. A secondary dining area makes this sophisticated home ideal for relaxed living and formal entertaining. Upstairs, retreat to the generous master suite with spa-like amenities including dual sinks, a soaking tub, a shower stall, and two closets. A loft is centrally located near the master and the remaining two bedrooms and bathroom. The private 8,712 square foot lot features a spacious concrete patio with a hot tub, lawn, and mature landscaping.
Listed at $779,900
Help Buyers Upgrade Their New Home
Buying an older home and need help with energy-efficient windows, HVAC upgrade, etc? When team up with Rojo Mortgage Team at UWL we can help you accomplish this.
When utilizing the Energy Efficient Mortgage (EEM) program on an FHA loan, the buyer not only gets energy-efficient windows, HVAC systems, solar electric systems, and cool roofs, but they also qualify for tax credits and rebates thru the new climate change legislation signed into law this month.
Help your new buyers or those refinancing, spruce up the house they are purchasing, making it more desirable while putting money back in their pockets. Money that will help cover the additional cost of MIP.
Take a look and call us today for more information. All FHA buyers/borrowers need to be made aware of the thousands of dollars they could receive back from the federal government.
Energy efficiency makes sense. EEMs are home loan programs designed to enable homebuyers to easily and affordably finance home energy upgrades with their mortgages. Effective insulation, modern central AC/Heating systems and fully weatherized doors and windows deliver more than a significantly lower monthly utility bill: they provide the amenities of happier living. Recommended and supported by the US Department of Energy and ENERGY STAR, EEM programs enable you to finance costly and valuable energy-related home improvements directly with your mortgage. Call us today 916-548-3942.
Rates Rising, Demand Weakens
The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($647,200 or less) increased to 5.65% from 5.45%.
"Last week's purchase results varied, with conventional applications declining 2% and government applications increasing 4%, which is potentially a sign of more first-time homebuyer activity," said Joel Kan, an MBA economist.
Mortgage demand continues to weaken, still right around a 22-year low, but there was a sign in the weekly numbers that first-time buyers may be slowly returning.
Mortgage applications to purchase a home fell 1% last week compared with the previous week, according to the Mortgage Bankers Association's seasonally adjusted index. Volume was 21% lower than the same week one year ago. There was, however, a jump in demand for loans offering lower down payments.
"Last week's purchase results varied, with conventional applications declining 2% and government applications increasing 4%, which is potentially a sign of more first-time homebuyer activity," said Joel Kan, an MBA economist.
He also noted that the average purchase loan size continued to trend lower, as homebuying at the high end of the market weakens.
Mortgage rates increased for all loan types last week. The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($647,200 or less) rose to 5.65% from 5.45%, with points climbing to 0.68 from 0.57 (including the origination fee) for loans with a 20% down payment.
As a result of the sharp increase in rates, demand for loan refinances dropped 3% for the week and were 83% lower than the same week one year ago.
Borrowers also moved away from adjustable-rate loans, which are no longer offering the bargains they did just a few months ago.
"The spread between conforming fixed-rate loans and ARM loans narrowed to 84 basis points from over 100 basis points the prior week," Kan said. "This movement made fixed rate loans relatively more attractive than ARMs, thereby reducing the ARM share further from highs seen earlier this year."
Mortgage rates moved even higher to start this week, as the stock market sold off on renewed fears of a recession. Investors are waiting for what they expect to be hawkish sentiment from the Federal Reserve at a meeting later this week in Jackson Hole, Wyoming.
Welcome to our Blog!

- Categories -
- Recent Posts -
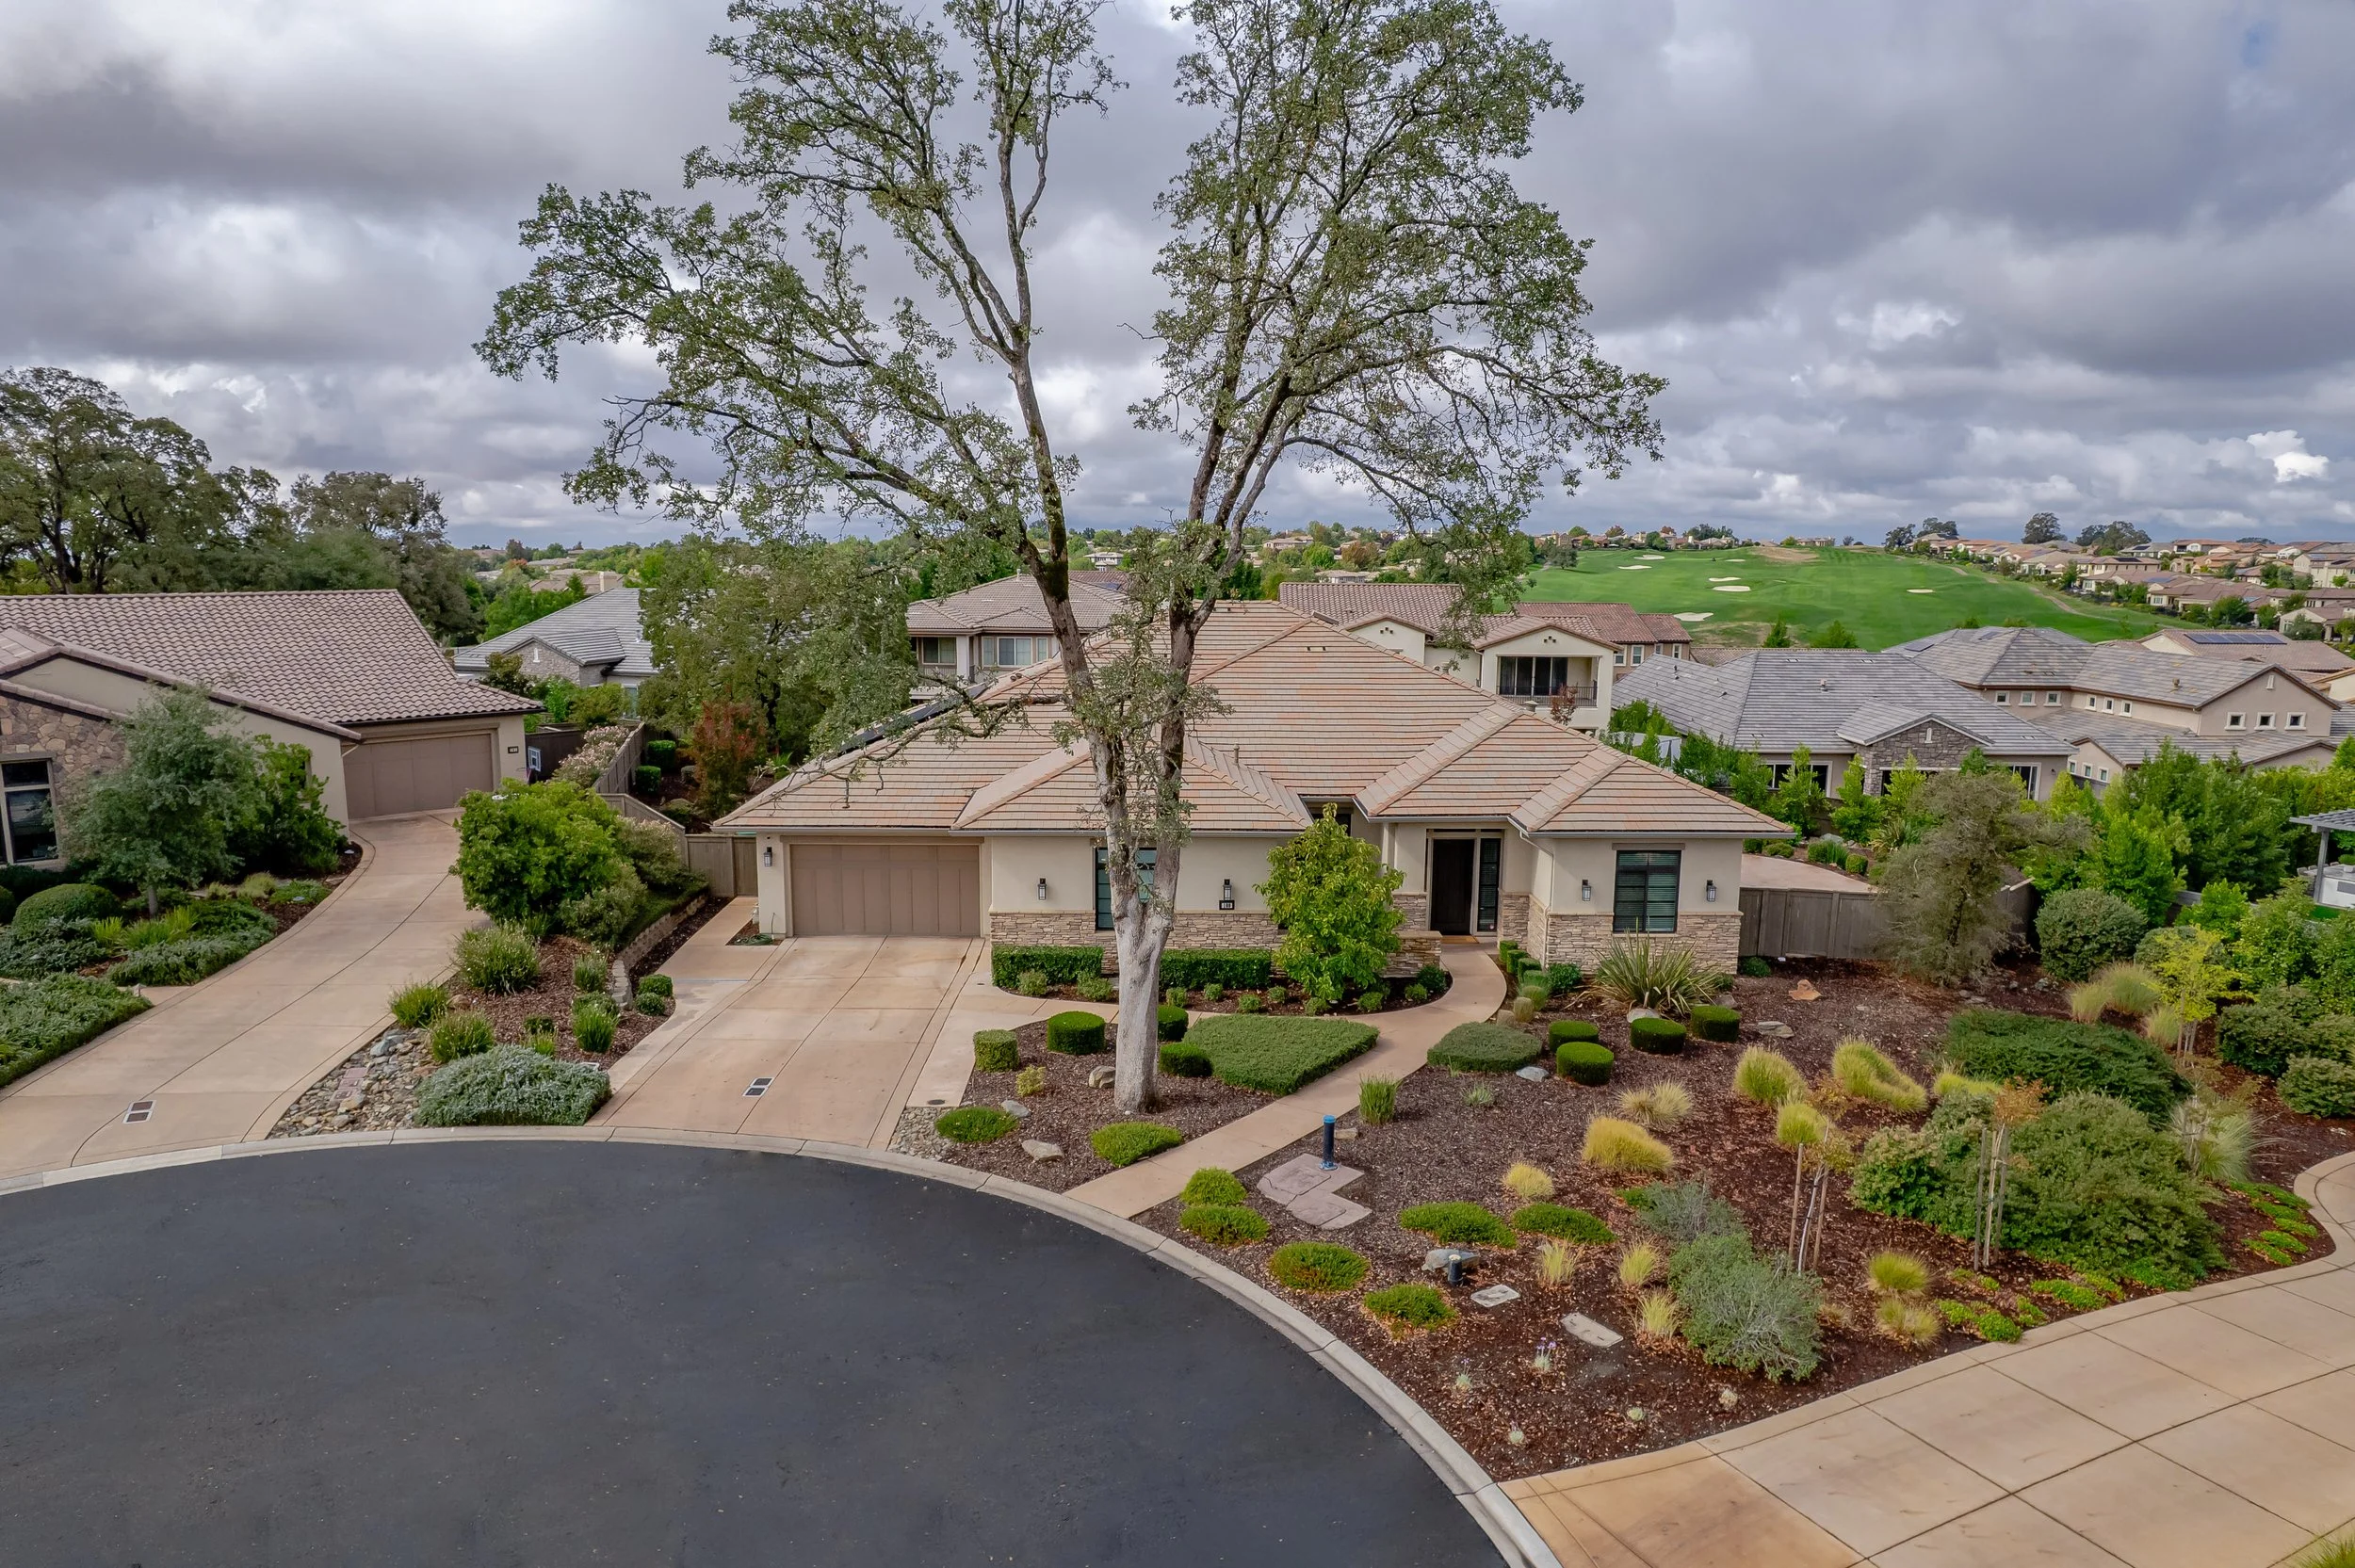


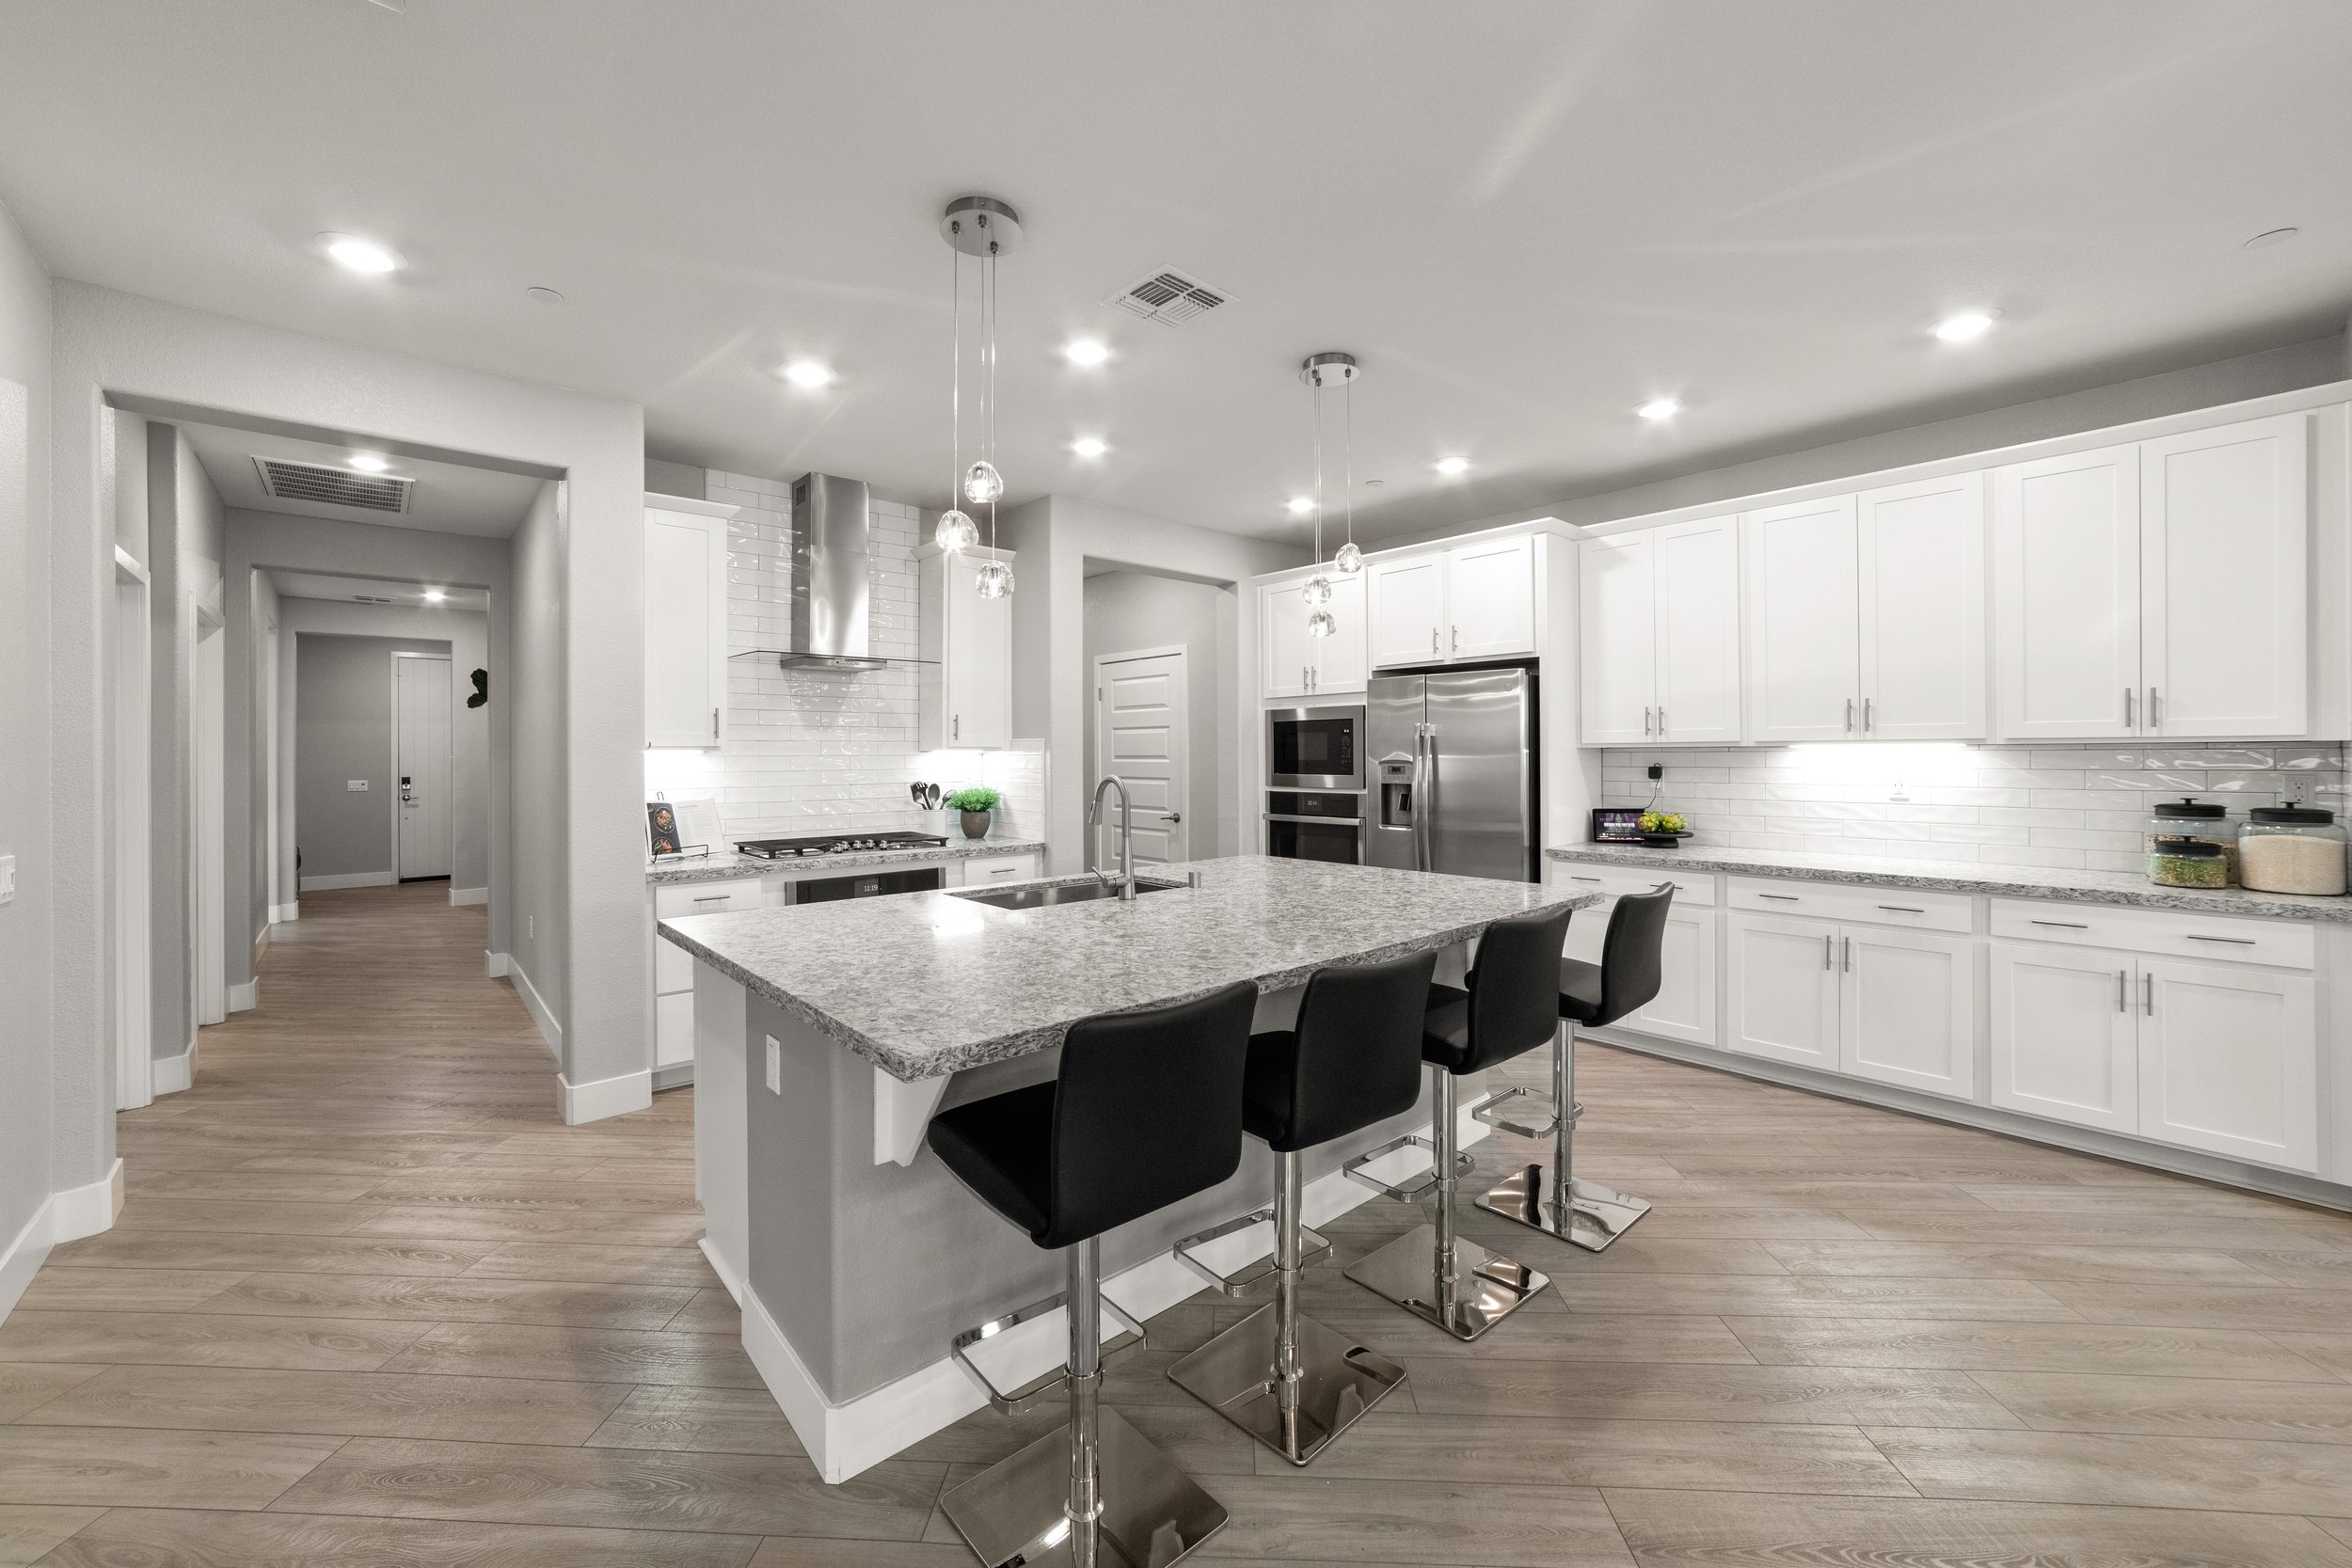
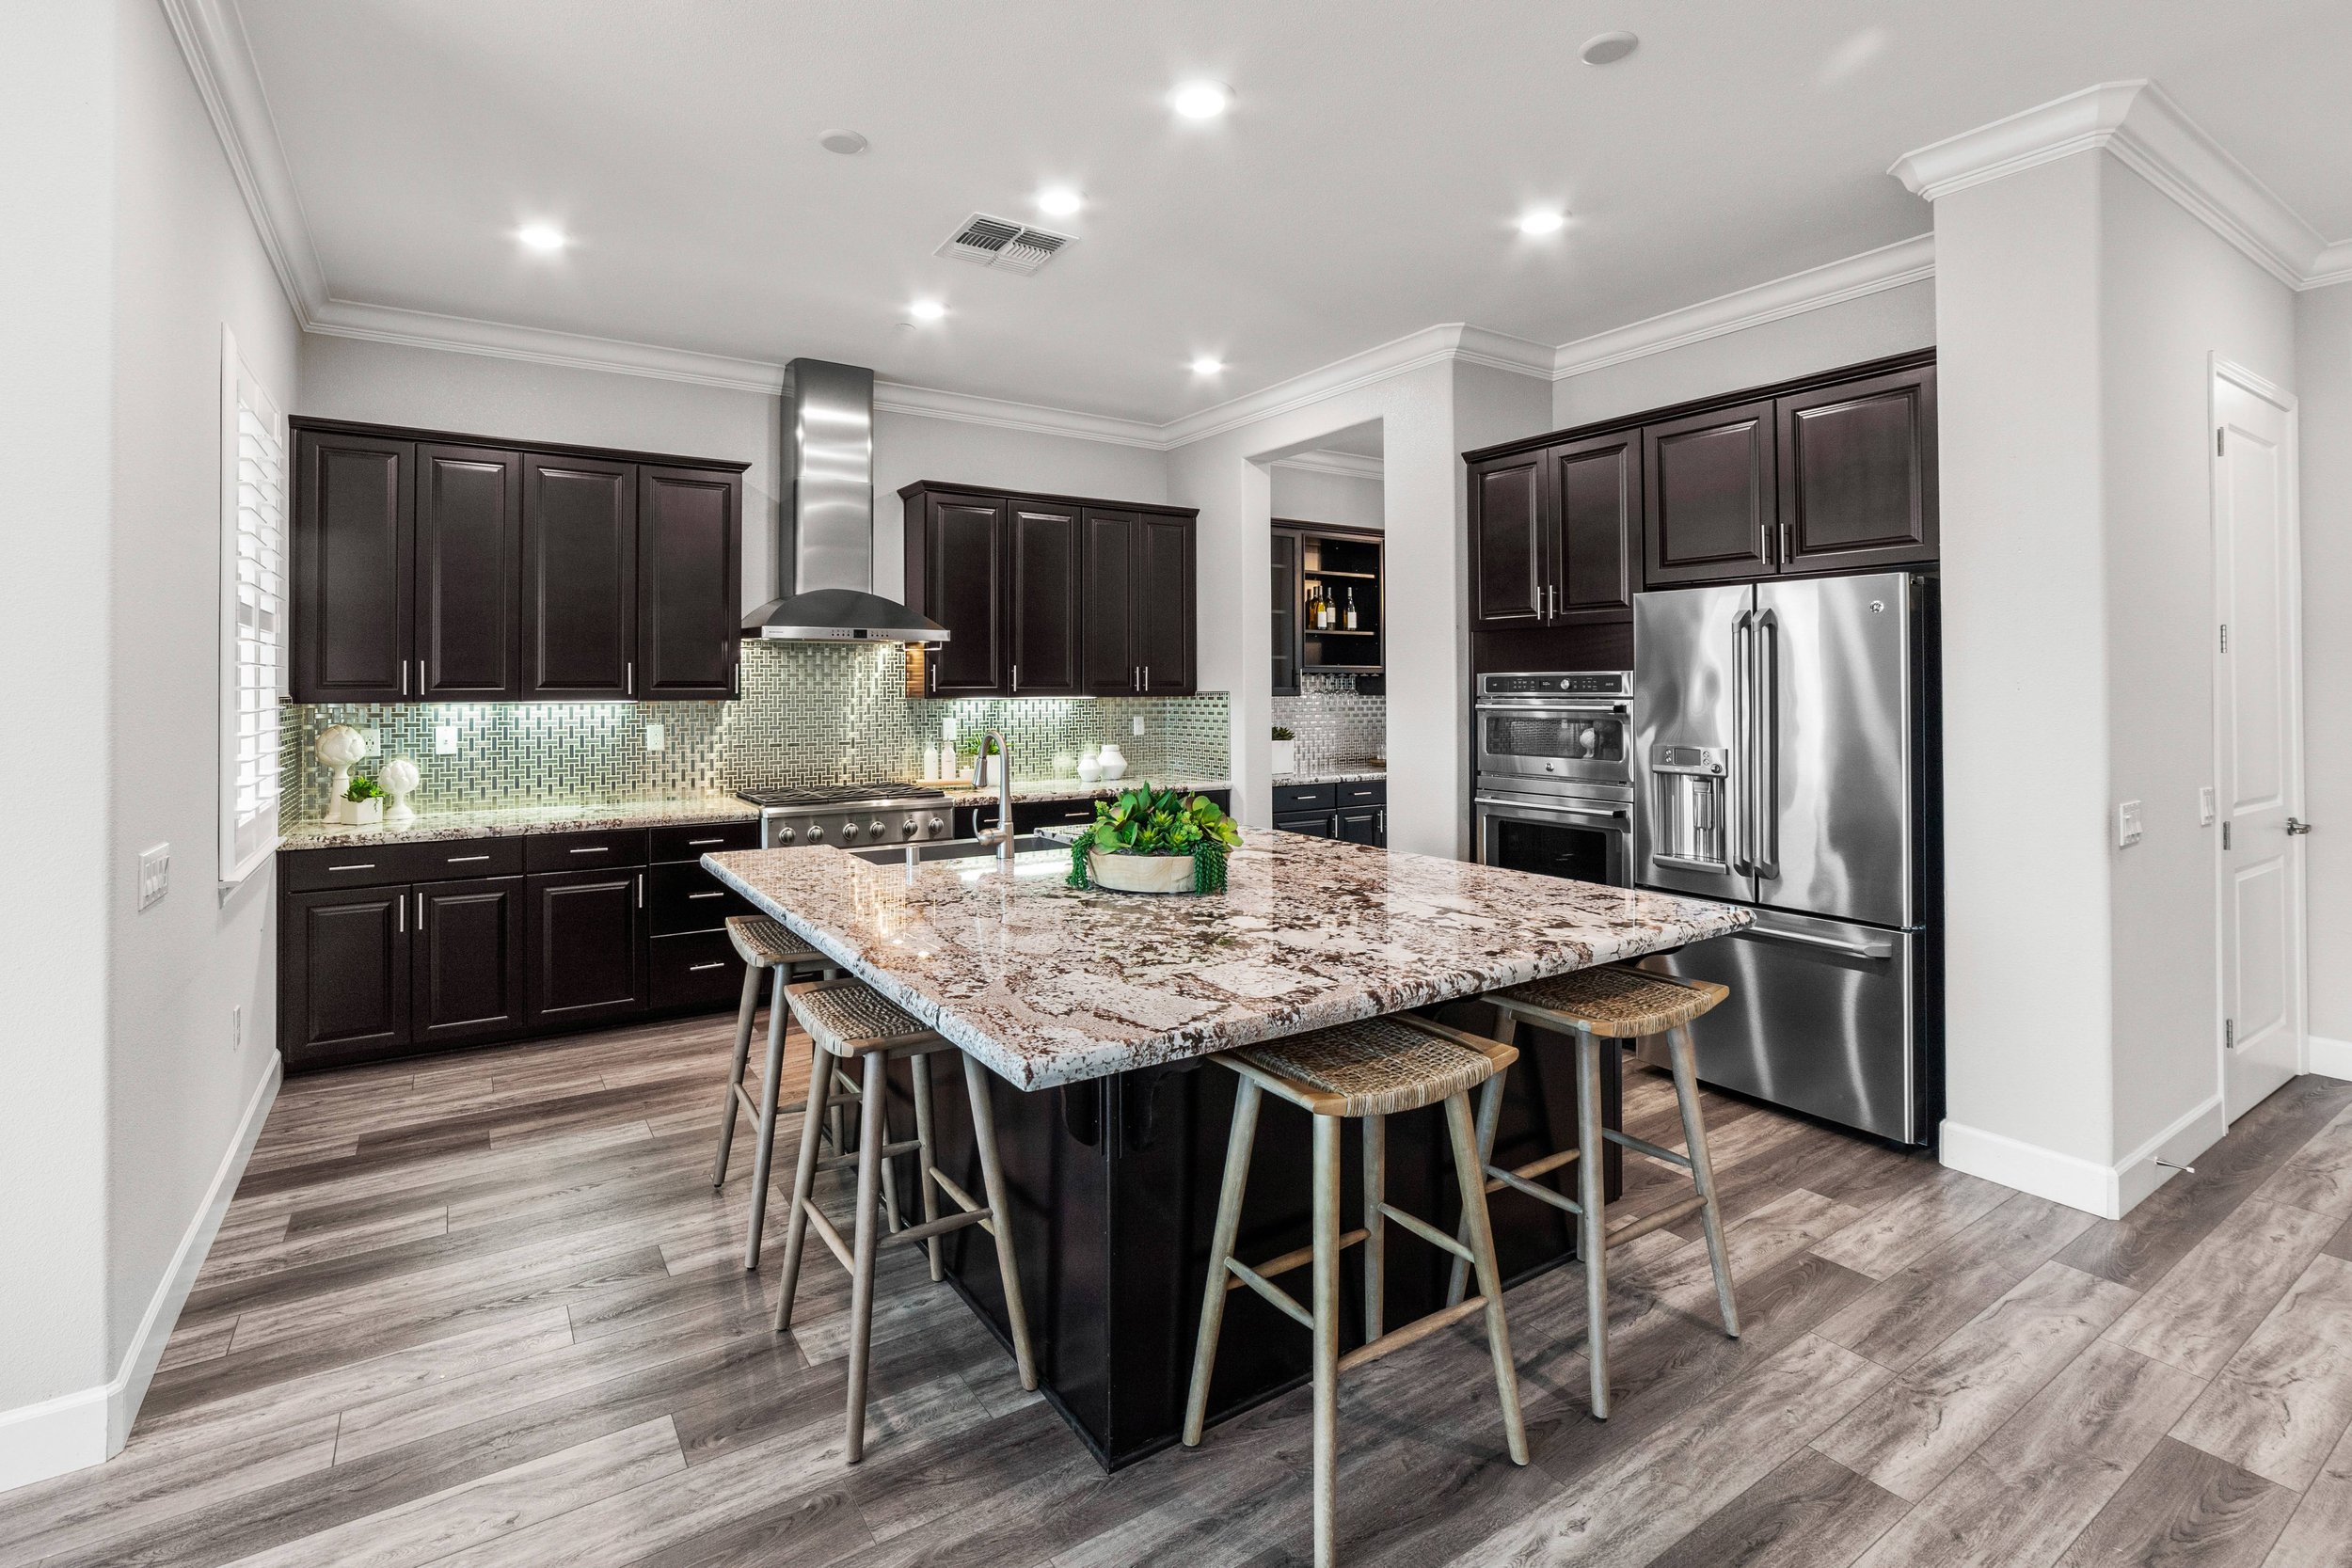

We helped our client purchase this Serrano home at a favorable price after it had been on the market for several months. When her relocation plans changed, she needed to sell without being here to manage the process.
The Menser Real Estate Group handled the preparation, staging, marketing, and negotiations, coordinating the details locally for our out-of-area client.
Our listing received two offers in just two days on the market. Approximately five months after her purchase, the home sold for $100,000 more than she had paid.
From purchase to resale, our team provided the local knowledge and hands-on support she needed as her plans changed.